
Ulster Bank Everyday Current Account: review 2026
Last updated: 29.10.2026
Contents
Summary
The Ulster Bank Select account (long marketed as the Everyday Current Account) scores 76 out of 100 in our assessment, offering a fee-free structure with 1.60% AER in-credit interest and a £200 switching bonus for eligible switchers who did not hold an Ulster Bank account on 26 May 2026. Eligibility is 18 or over and a UK resident, not Northern Ireland residency, though branch access remains concentrated in Northern Ireland. The high overdraft rate of 39.49% EAR makes it a poor fit for anyone who regularly dips into the red.
Pros
- No monthly account fee
- 1.60% AER interest paid monthly on the current account balance
- £200 switching bonus for switchers without an Ulster Bank account on 26 May 2026
- Apple Pay and Google Pay both supported
- joint account option available
Cons
- Non-sterling ATM withdrawals and card purchases carry a 2.65% fee
- overdraft EAR of 39.49% is high by modern standards
- branch network is concentrated in Northern Ireland and has been shrinking
- no virtual card number for online shopping
Key facts
| Monthly fee | £0 |
| Debit card | ✓ |
| Credit card | ✗ |
| Apple Pay | ✓ |
| Google Pay | ✓ |
| Cash withdrawal abroad | 2.65% non-sterling fee |
| Online account opening | ✓ |
| Deposit protection | £120,000 |
| iOS app | ✓ |
| Branches | ✓ |
| Rating | 3.8 /5 |
Strengths in detail
How well the provider covers the most important areas.
A closer look
What is the Ulster Bank Everyday Current Account and who is it for?
Ulster Bank occupies a peculiar niche in the UK banking landscape. It is not a national bank in the conventional sense. Since 2023 it has operated exclusively in Northern Ireland, having withdrawn its retail presence from the Republic of Ireland and scaled back its footprint considerably. The account reviewed here, long marketed as the Everyday Current Account, now appears on Ulster Bank's own application pages under a new name: the Select account. We've kept the familiar name in this review because that's what most readers search for, but don't be surprised to see "Select account" on the bank's site and on your statements. It is the bank's flagship personal banking product, and it suits a specific type of customer rather well: someone who values a relationship with a branch-based high-street bank, wants no monthly fee, and is comfortable with the traditional infrastructure of Visa debit, mobile banking, and in-person service.
In our test the account was opened fully online without visiting a branch, which matters given Ulster Bank has been closing sites at pace. The digital onboarding works well, but the experience still feels built for someone who might want to pop into a branch occasionally. There's no credit card attached to the account, no premium tier with travel insurance bundled in, and no savings pot feature woven into the app. It's a genuinely no-frills current account doing exactly what a no-frills current account should do. How it stacks up against the rest of the market is shown here: Best joint savings account.
Who is this account not for? Ulster Bank's own application page lists the eligibility rule as 18 or over and a UK resident, with no Northern Ireland address required, so it isn't the Northern-Ireland-only product it once was. What's genuinely Northern-Ireland-concentrated is the branch network: if you want face-to-face service, you'll need to live near one of the remaining branches, and those are all in Northern Ireland. Frequent international travellers will find the 2.65% non-sterling fee on ATM withdrawals and card purchases abroad a genuine irritant. Heavy overdraft users should also look carefully at the 39.49% EAR before signing up, which sits at the upper end of the market. We lined up the closest Chase alternatives side by side.
Real costs and fees you need to know
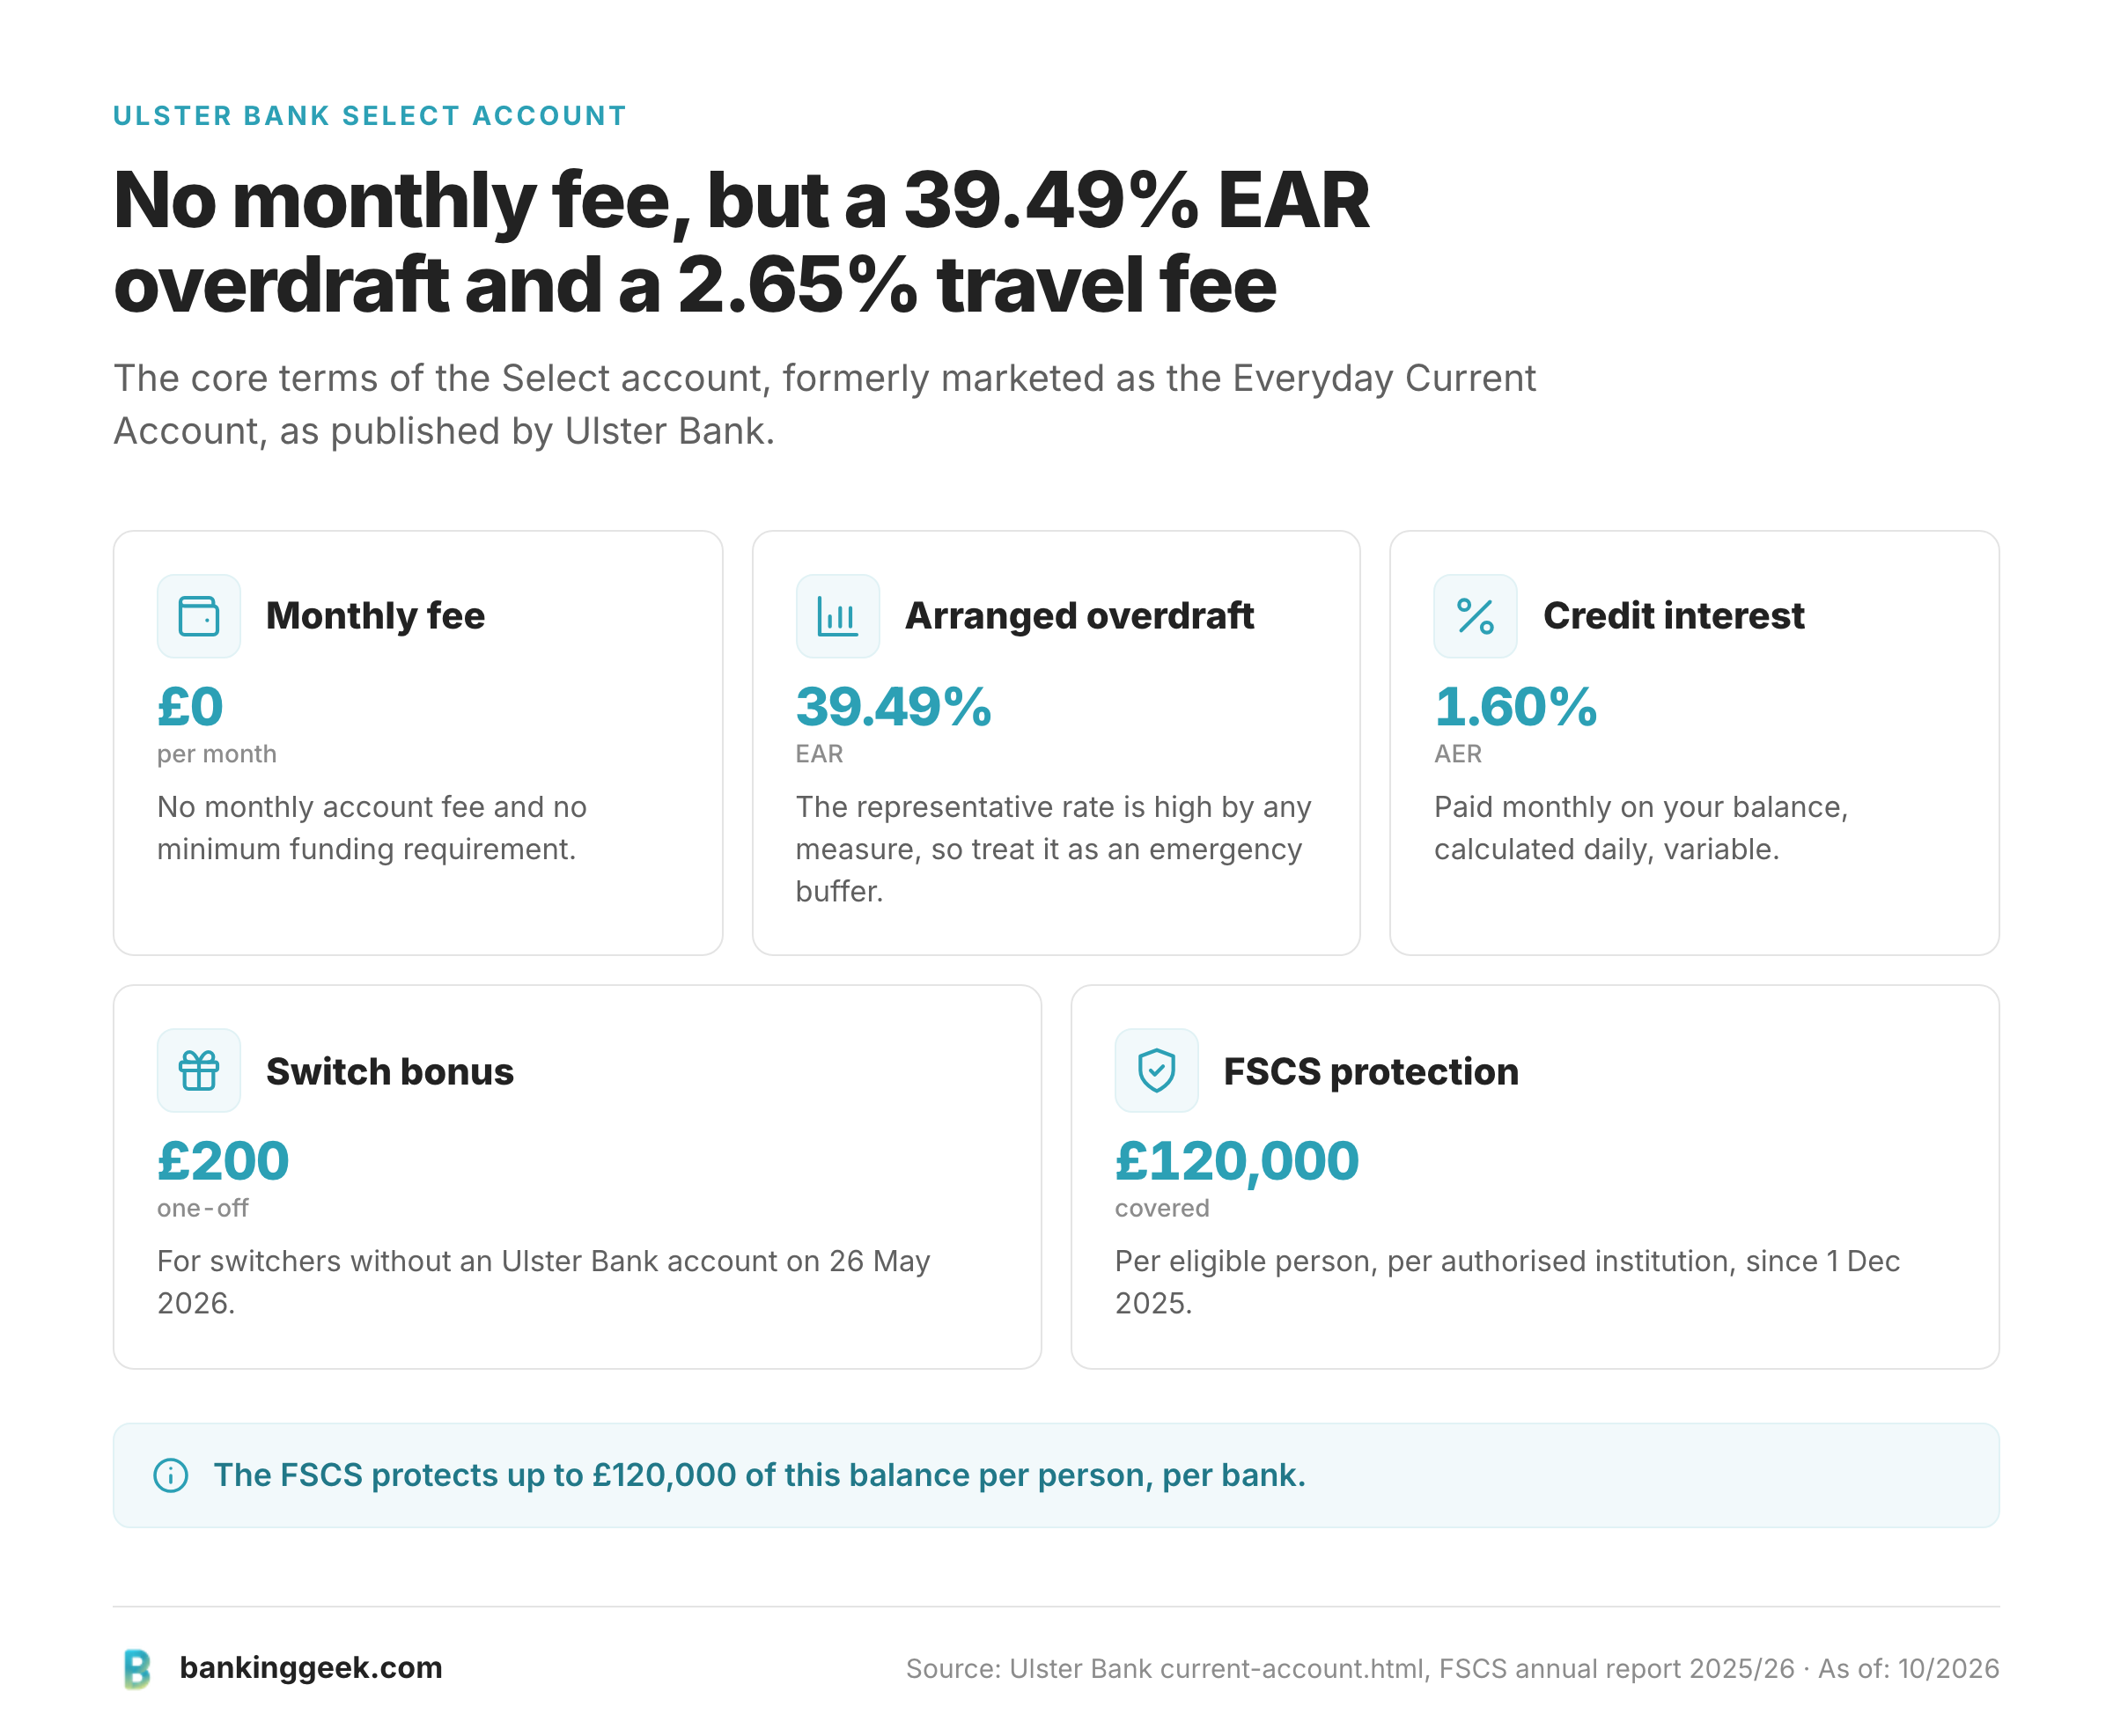
The headline figure is simple: the monthly account fee is £0. That makes the account genuinely competitive against many packaged or premium accounts from large UK banks that charge £5 to £25 per month. The fee-free positioning is real, not a teaser rate. There's no minimum funding requirement to avoid a dormancy charge, and standard UK payments including Faster Payments, BACS, and standing orders carry no transaction fee. If you are still shopping around, start here: Chase vs Monzo.
The complications emerge at the edges. Non-sterling ATM withdrawals attract a 2.65% fee, which applies both in Europe and globally. A cash withdrawal of £200 in, say, a Spanish resort costs you an extra £5.30. Over a two-week holiday that adds up. Card purchases made in foreign currencies carry the same non-sterling loading, so paying a hotel bill in euros with your Ulster Bank Visa debit card is not cheap. There is no fee-free foreign currency allowance.
Overdraft pricing deserves attention. The EAR of 39.49% is high by any measure. NatWest, which owns Ulster Bank, charges a similar rate on its own current accounts, so this is a group-level pricing decision rather than something unique to Ulster Bank. Arranged overdrafts are available, but if you regularly dip below zero, the annual cost at that rate accumulates fast. An unauthorised overdraft carries its own charges. Always treat the overdraft facility as an emergency buffer, not a routine funding source.
Instant transfers using Faster Payments are included at no extra cost within the standard account. There is no premium tier or additional charge for sending money to another UK account. That is worth noting because some challenger banks have introduced fees for instant transfers on their basic tiers.
Cards, contactless payments and spending limits
The account comes with a Visa debit card. There is no credit card option attached to this product; Ulster Bank does not bundle a credit facility. The Visa debit works anywhere Visa is accepted globally, which covers the vast majority of merchants. Contactless payments currently work up to £100 per transaction without PIN entry. The UK regulator lifted the fixed nationwide £100 cap from March 2026, so providers can now set their own limit, but NatWest Group, which runs Ulster Bank's card platform, says it's keeping £100 for the time being. That's a genuinely useful thing to know before you travel, since some other providers have already moved the goalposts.
Apple Pay and Google Pay are both fully supported. In our test, adding the card to an iPhone wallet took under two minutes. Once registered, the digital wallet can be used for contactless payments above the £100 physical card limit because biometric authentication satisfies the strong customer authentication requirement. That is a practical benefit when paying for larger purchases at a tap terminal.
There is no virtual card number for online shopping, which is a gap compared with some digital-first competitors. Monzo and Starling, for example, offer disposable virtual card numbers for one-off online transactions. Ulster Bank does not offer this. For online purchases the physical card number is used, and fraud protection relies on the standard Visa chargeback mechanism and Ulster Bank's fraud monitoring systems rather than any card-number isolation feature. If it is not the right fit, we compared the strongest Monzo alternatives.
Opening the account: step by step
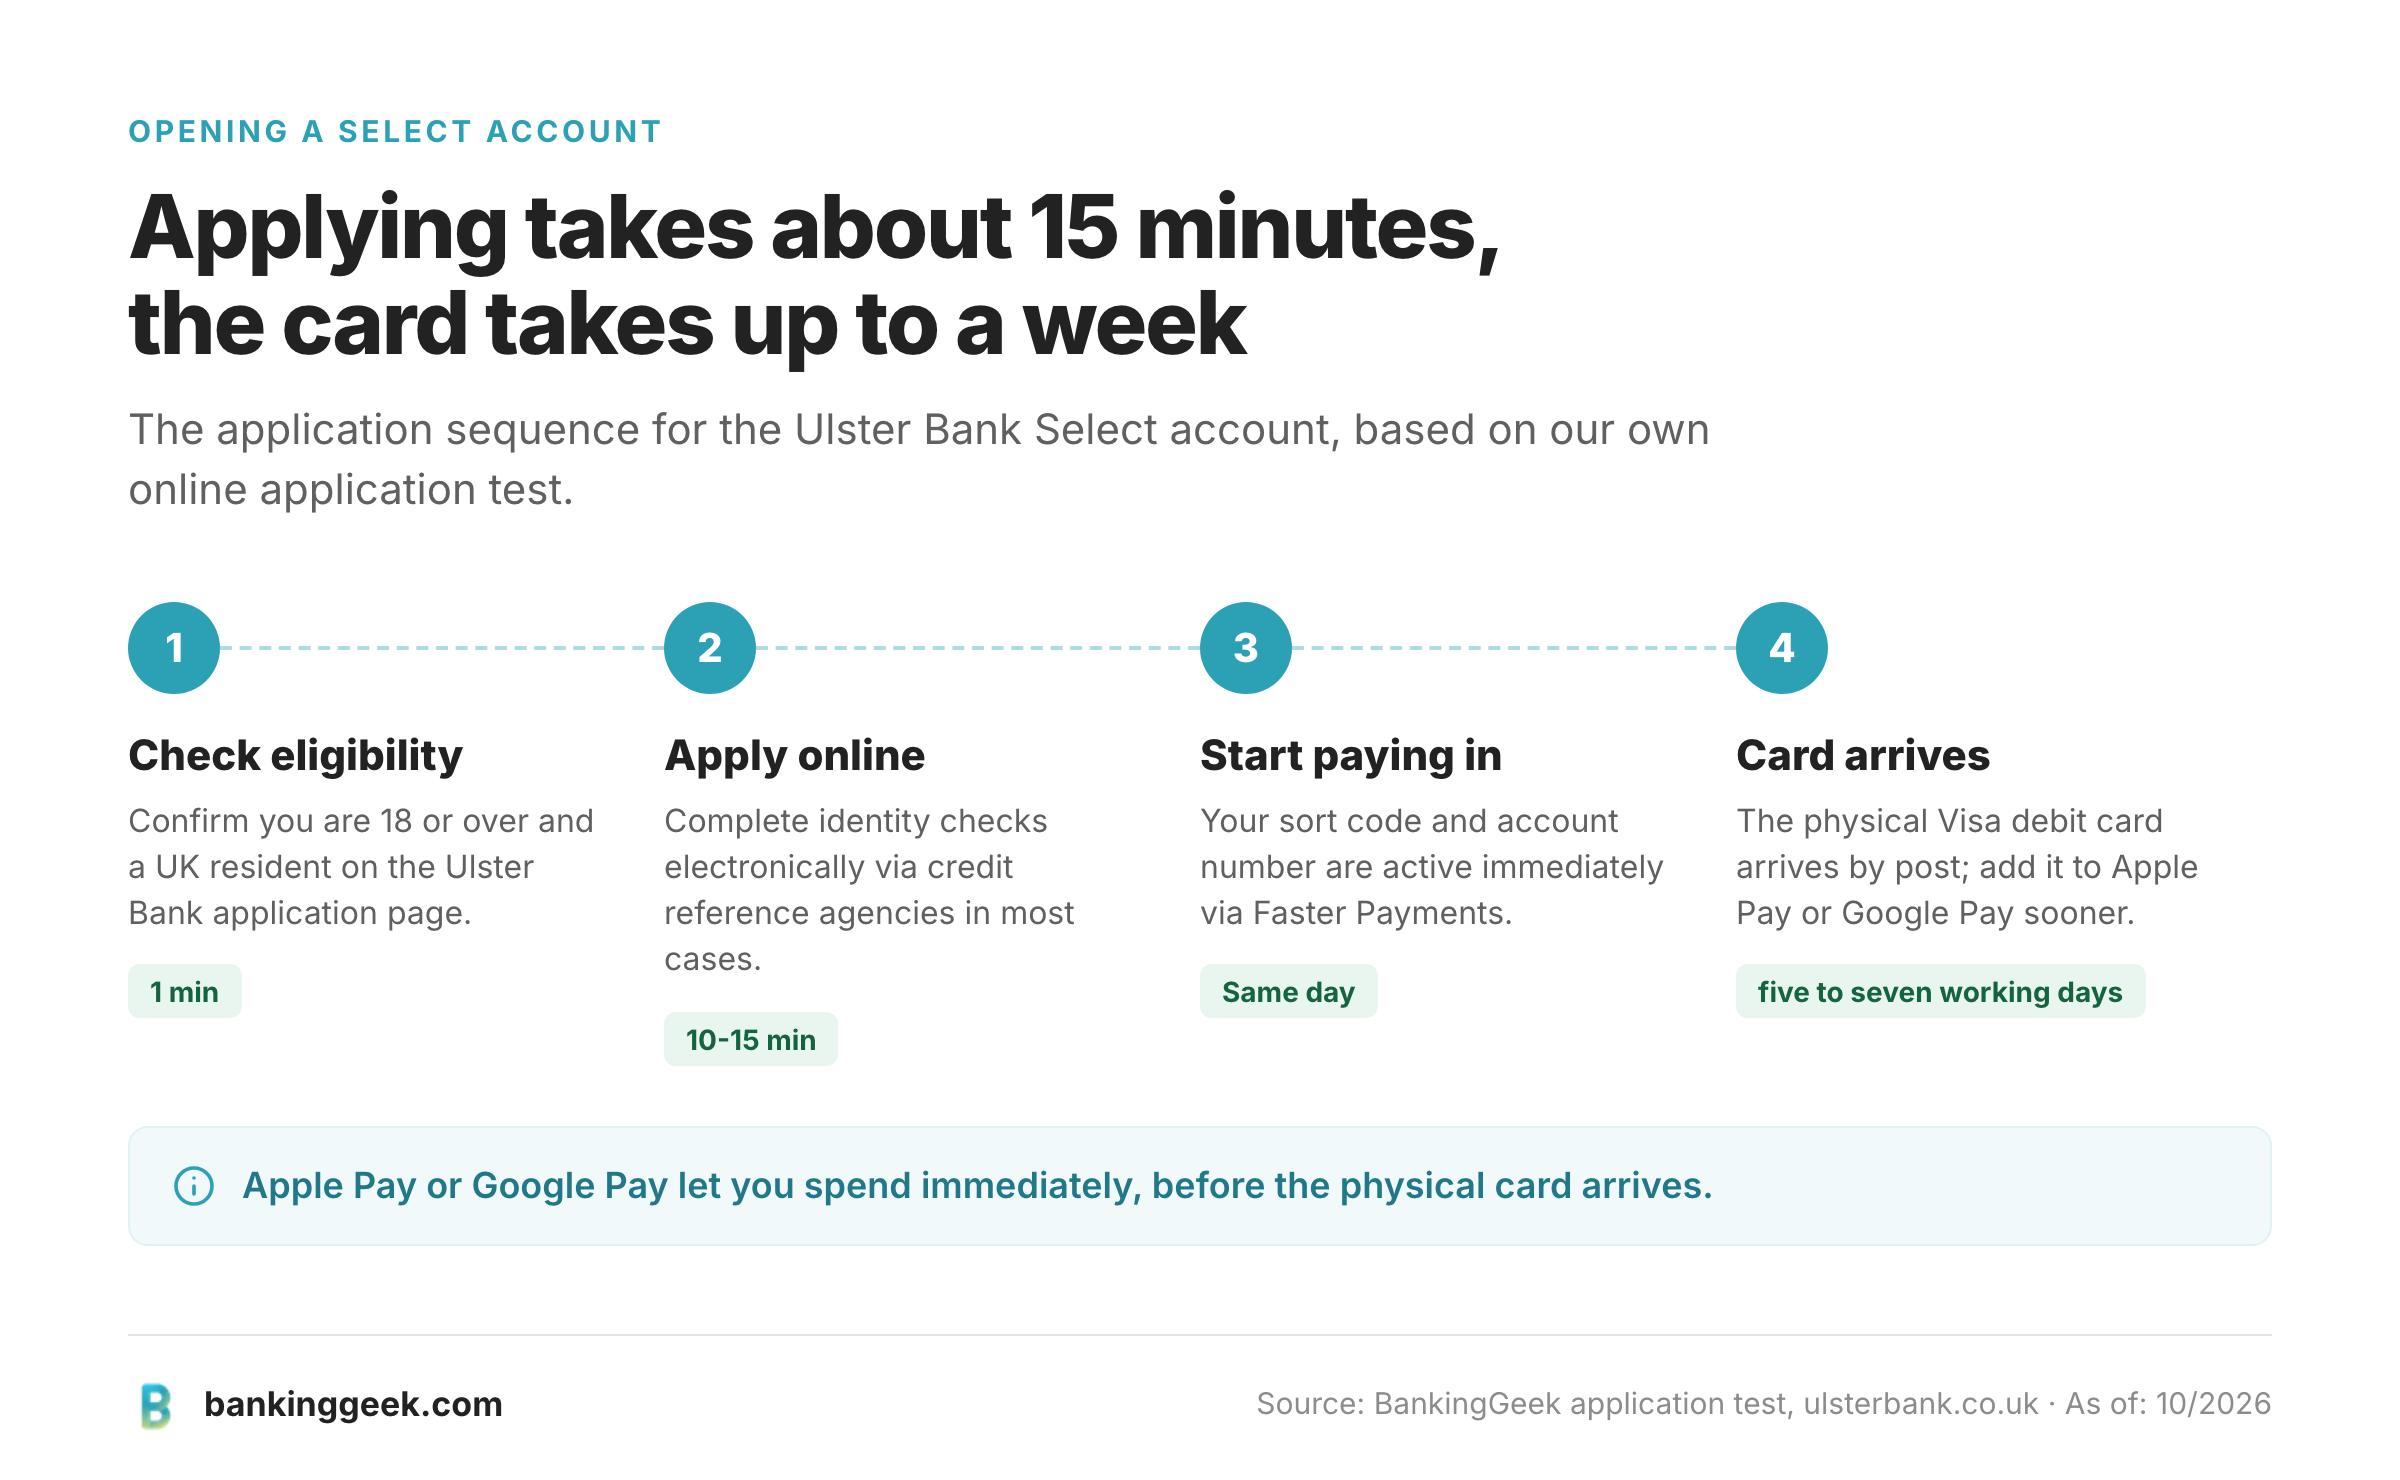
The application is completed online at ulsterbank.co.uk. You need to be 18 or over and a UK resident; Ulster Bank's application page does not ask for a Northern Ireland address as a condition of eligibility. The bank verifies identity electronically using credit reference agency checks in most cases, though some applicants may be asked to provide documentation in branch or by post. The process takes roughly 10 to 15 minutes to complete online.
Once approved, the account IBAN carries a GB prefix. The sort code is a standard six-digit UK sort code, and the account number is the familiar eight digits. Paying in can begin immediately via Faster Payments from another UK account. The physical Visa debit card arrives by post within five to seven working days. A temporary card or instant virtual card is not offered while you wait, which means the account is not immediately usable for in-store purchases without Apple Pay or Google Pay already being configured.
Joint accounts are available and follow the same application process with identity verification for both applicants. There is no separate product for joint accounts; the account can simply be applied for jointly from the outset. Note that both account holders will have equal access and equal liability, which is the standard arrangement for joint current accounts under UK banking regulation.
Switching to Ulster Bank from another UK current account can trigger a £200 bonus payment under its current switch offer. The published terms exclude anyone who already held an Ulster Bank current account on 26 May 2026, and funds moved during the switch count towards a £1,250 paying-in requirement. The switch itself uses the Current Account Switch Service guarantee, which handles the redirection of direct debits and standing orders automatically within seven working days. Ulster Bank says this offer may be changed, replaced or withdrawn at any time, so don't assume it's still running without checking the live terms first.
The app, digital features and customer service
Ulster Bank has native apps for iOS and Android. The iOS app carries a reasonable rating on the App Store, and core functionality works reliably: balance checking, payment initiation, direct debit management, and transaction history with simple categorisation. The app connects to the wider NatWest Group infrastructure, which means some features and the underlying security architecture are shared with NatWest and Royal Bank of Scotland, which markets the same Select account branding.
The feature set is functional without being remarkable. You can freeze and unfreeze your card within the app, which is a genuinely handy habit if you've ever misplaced a wallet. Spending notifications appear after transactions. You can set travel notifications before a foreign trip, which reduces the chance of payments being declined abroad on suspicion of fraud. There is no built-in savings pot feature comparable to what Monzo or Starling offer, and no round-up savings mechanism. The account is a current account and the app reflects that without embellishment. We put the competition side by side here: Monzo vs Chase.
Customer service runs through telephone banking, the branch network, and in-app messaging. The branch network is shrinking. Ulster Bank has closed a number of Northern Ireland branches in recent years, and further closures have been signalled. For customers in rural areas, the practical availability of face-to-face banking is diminishing. Telephone waiting times during busy periods can be lengthy, which is a complaint that surfaces regularly in customer reviews. The in-app messaging route is slower than telephone for urgent issues but avoids hold times for non-urgent queries.
Reputation and real customer experience
Customer sentiment around Ulster Bank is genuinely mixed, and the split tends to follow a clear pattern. Longer-standing customers who have used the bank for years and appreciate the Northern Ireland community presence rate it warmly. They cite the reliability of the core account, familiarity with the staff in remaining branches, and the stability of a bank backed by a large group. The 1.60% AER interest paid monthly on the current account balance is mentioned positively, as most current accounts in the UK pay nothing.
The recurring complaints are structural rather than operational. Branch closures generate consistent frustration, particularly among customers who relied on local branches and now face significant travel to reach the nearest open one. Telephone waiting times appear repeatedly as a pain point, with some reviewers describing 30-minute or longer holds for straightforward queries. There is also frustration among customers who have moved from Northern Ireland to Great Britain and found face-to-face support effectively out of reach, even though the account itself can still be kept open.
The NatWest Group ownership provides institutional solidity but it also shapes perceptions. Some customers feel Ulster Bank's distinct identity is diminishing as it is absorbed further into group systems, and the rename of its flagship account to the group-wide Select branding is one more sign of that. That is a reputational consideration rather than a functional one, but it colours how long-term customers talk about the bank. No independently verified satisfaction score is cited here, but the thematic pattern across review platforms is consistent: core banking works, the shrinking physical network frustrates.
Verdict: open this account or look elsewhere?
This account, now branded the Select account, genuinely makes sense for a specific customer. Anyone in the UK who wants a fee-free current account with a recognisable high-street name, Apple Pay and Google Pay support, and a mild interest rate of 1.60% AER on their balance will find it adequate and refreshingly inexpensive. Northern Ireland residents get an added bonus: a shrinking but still-present branch network. The £200 switching bonus, open to switchers who didn't already hold an Ulster Bank account on 26 May 2026, is a solid incentive that shifts the value calculation further in the account's favour for the first year, as long as the offer's still live when you check.
Safety isn't a concern here. The account is covered by the Financial Services Compensation Scheme up to £120,000, regulated by the Financial Conduct Authority and Prudential Regulation Authority, and backed by NatWest Group. The FSCS limit rose from £85,000 to £120,000 on 1 December 2025. Interest received on the current account balance counts toward your Personal Savings Allowance: £1,000 per tax year for basic-rate taxpayers, £500 for higher-rate taxpayers, with interest taxed as income above those thresholds.
Look elsewhere if you travel regularly, use an overdraft routinely, or simply don't need a branch anywhere near you. The 2.65% non-sterling fee is a real cost for travellers. The 39.49% EAR overdraft is genuinely punishing for those who run close to zero. Chase UK, Starling, and Monzo offer fee-free current accounts with no branch network at all, generally better foreign transaction terms, and richer app features. For a digital-first customer who never wanted a branch in the first place, those alternatives deserve serious comparison.
How safe is Ulster Bank Everyday Current Account?
Ulster Bank Everyday Current Account vs alternatives
A direct comparison of the key conditions against the strongest competitors in the market.
 |  |  |  | |
| Rating | 3.8 /5 | 5.0 /5 | 5.0 /5 | 5.0 /5 |
| Monthly fee | £0 | £0/month | £0/month | £0/month |
| Debit card | ✓ | ✓ | ✓ | ✓ |
| Credit card | ✗ | ✗ | ✗ | ✓ |
| Apple Pay | ✓ | ✓ | ✓ | ✓ |
| Google Pay | ✓ | ✓ | ✓ | ✓ |
| Cash withdrawal abroad | 2.65% non-sterling fee | Free up to £200/30 days; then 3% (Perks/Max: £600/30 days) | Free (no Starling fees) | No fee; up to £1,500/month abroad |
| Online account opening | ✓ | ✓ | ✓ | ✓ |
| Deposit protection | £120,000 | £120,000 | £120,000 | £120,000 |
| iOS app | ✓ | ✓ | ✓ | ✓ |
| Branches | ✓ | ✗ | ✗ | ✗ |
How we rate
About the author
Frequently asked questions
The account is open to UK residents aged 18 or over, but in practice Ulster Bank's personal banking services are focused on Northern Ireland. You can apply online, though the branch network for in-person support is concentrated in Northern Ireland rather than across Great Britain.
There is no monthly fee. The account costs £0 per month to maintain, with no minimum funding requirement. Costs arise only from specific transactions such as non-sterling ATM withdrawals, which carry a 2.65% fee.
Deposits are protected under the FSCS (Financial Services Compensation Scheme) up to £120,000 per person per bank. Ulster Bank is authorised by the PRA and regulated by the FCA and PRA, so the protection applies in full.
You can apply online via the Ulster Bank website. Most applications are completed in around fifteen to twenty minutes and a same-day decision is common for straightforward cases. You will need proof of identity and a UK address.
Yes. The account uses biometric login, two-factor authentication for payments, and real-time fraud alerts. Ulster Bank is a regulated UK bank covered by FSCS protection, and the app supports instant transaction notifications to flag any unusual activity.
Interest of 1.60% AER is paid gross each month. Under the Personal Savings Allowance, basic-rate taxpayers can earn up to £1,000 in savings interest per year before paying income tax, so most customers with typical current account balances will owe nothing. Higher-rate taxpayers have a lower allowance of £500.