
Monzo Current Account review 2026: fees, features and verdict
Last updated: 02.11.2026
Contents
Summary
Monzo is one of the UK's best-known digital banks, offering a free current account packed with real-time spending notifications, budgeting pots and a sleek mobile app. The free tier gives you everything you need for everyday banking with no monthly fee, while paid plans (Monzo Extra, Monzo Perks and Monzo Max) layer on higher savings interest, perks and (with Max) travel insurance for a monthly charge. There are no physical branches, but Monzo's in-app support and user experience consistently rank among the highest in the country. Fully regulated by the FCA and protected by the FSCS up to £120,000, it is a credible main-bank option for digitally confident customers.
Pros
- Free account with no monthly fee and no minimum deposit
- Real-time push notifications for every transaction
- Savings Pots with competitive interest rates (including locked pots)
- Highly rated app with budgeting tools, bill splitting and salary sorter
- FSCS-protected up to £
- 120,000
Cons
- No physical branches -- all support is in-app or by phone
- Overdrafts are not guaranteed and carry daily usage fees
- Best interest rates and travel perks require a paid subscription
Key facts
| Monthly fee | £0/month |
| Debit card | ✓ |
| Credit card | ✗ |
| Apple Pay | ✓ |
| Google Pay | ✓ |
| Cash withdrawal abroad | Free up to £200/30 days; then 3% (Perks/Max: £600/30 days) |
| Online account opening | ✓ |
| Deposit protection | £120,000 |
| iOS app | ✓ |
| Branches | ✗ |
| Rating | 5.0 /5 |
Strengths in detail
How well the provider covers the most important areas.
A closer look
What Monzo is and who it suits
Monzo launched in 2015 as a prepaid card experiment and grew into one of the UK's most recognisable digital banks. Today it holds a full UK banking licence granted by the Prudential Regulation Authority, meaning your deposits sit inside the Financial Services Compensation Scheme up to £120,000. The FSCS limit rose from £85,000 to £120,000 on 1 December 2025. That matters more than it might sound: not every fintech carries a full licence, and some rely on e-money institution status, which provides weaker protection. For anyone deciding where to keep a salary, that distinction is non-negotiable.
The account works best for people who manage money primarily through a smartphone. If you check your balance the old-fashioned way, at a branch window with a passbook, Monzo will frustrate you from day one. There are no physical branches, no telephone banking in the traditional sense, and no cheque book. But for someone who wants instant spending alerts, rule-based savings pots, split-bill tools, and a clean overview of where their salary goes, this is genuinely one of the strongest offerings on the UK high street, digital or otherwise. An overview of the Monzo alternatives is in a separate article.
Monzo isn't for people who regularly pay in cash, need a business overdraft facility as standard, or want a relationship manager to call when something goes wrong. It isn't ideal for those who keep large savings parked in a current account: the main current account balance itself earns 0% interest, and the free plan's Instant Access Pots pay 2.75% AER (variable), rising only modestly on the paid plans. If your main goal is earning on a large cash buffer, a dedicated easy-access savings account will serve you better.
FSCS protection scales with account type. A single Monzo account is covered up to £120,000. On a joint Monzo account, each holder is separately entitled to that £120,000 limit, giving a combined £240,000 of protection on the one account.
Real costs and hidden fees
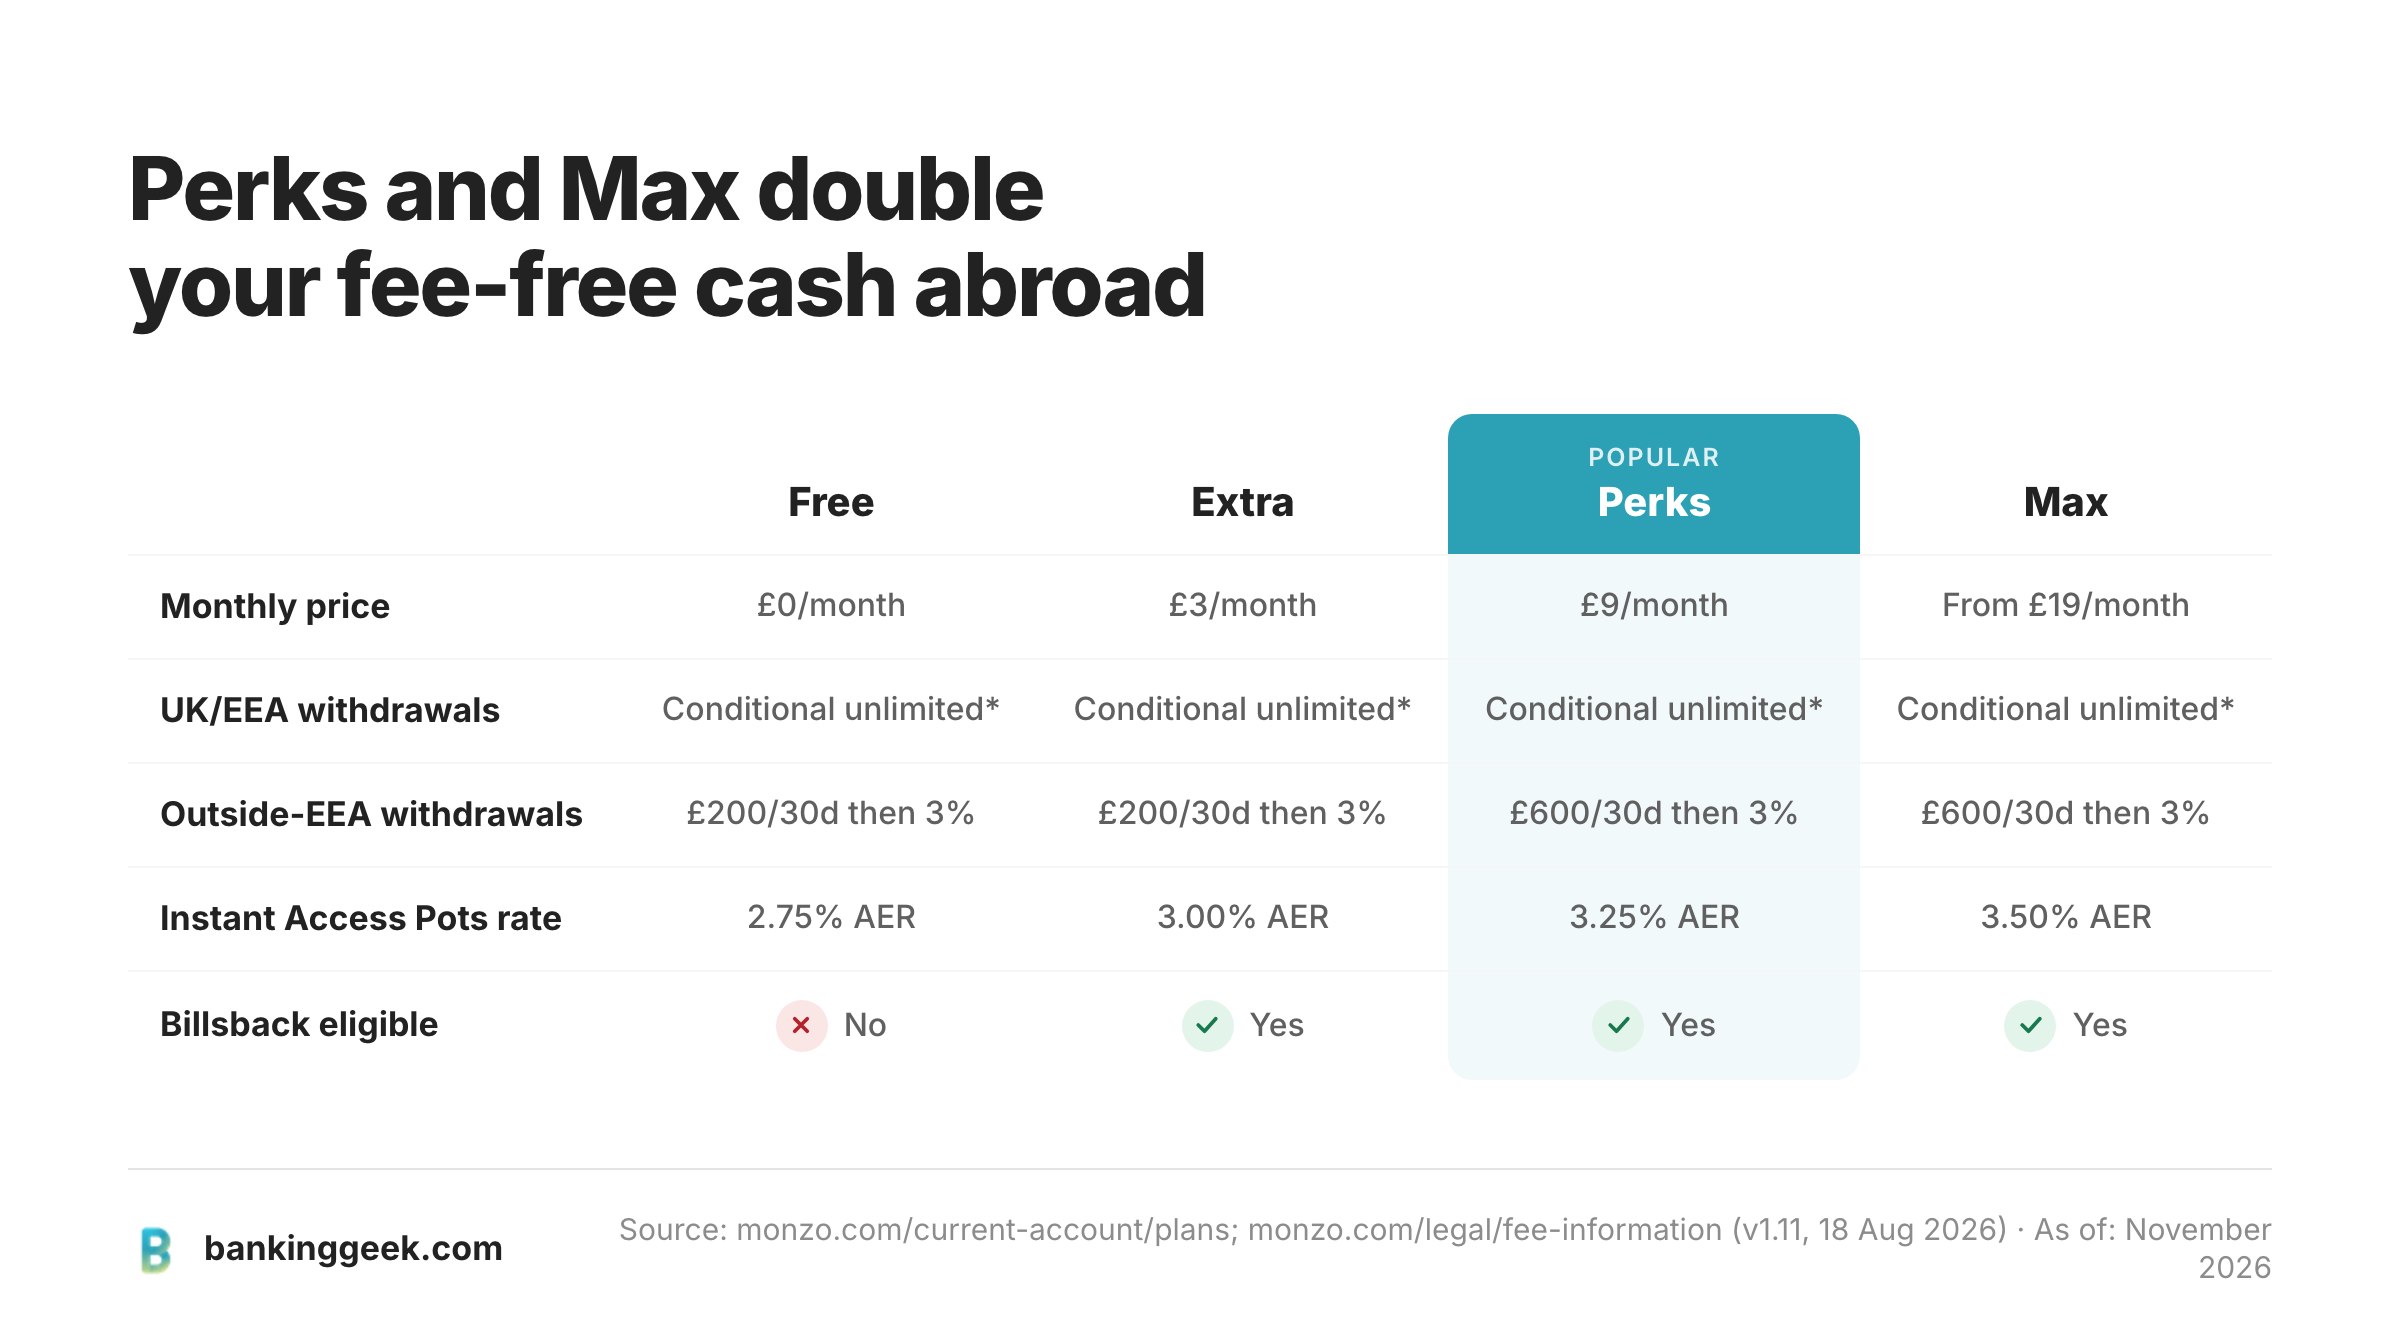
The headline cost is straightforward. Monzo's standard current account carries a monthly fee of £0. The coral Mastercard debit card is included with no annual charge. Card spending, in the UK and abroad, is fee-free on every tier with no monthly cap. Cash withdrawals are where the tiers and conditions matter: in the UK and the EEA, withdrawals are fee-free with no limit only if you meet Monzo's "Fee Criteria" (broadly, at least £500 paid into the account over a rolling 35-day period plus an active Direct Debit, i.e. using Monzo as your main bank). If you don't meet that criteria, UK and EEA withdrawals combined are fee-free up to £400 per rolling 30 days, then 3% on the excess. For cash withdrawn outside the EEA, the free allowance is £200 per rolling 30 days on the free account and Monzo Extra, rising to £600 on Monzo Perks and Monzo Max, again with a 3% fee above that. We compared both providers side by side in Monzo vs Chase.
Sending money within the UK via Faster Payments is free and instant. Scheduled standing orders and direct debits carry no charge. CHAPS transfers, which you might need for a house purchase or a large business payment, aren't available directly through the app, though Faster Payments covers most everyday transfers instead; the gap matters only to the minority who need a same-day CHAPS payment.
Monzo Extra costs £3 per month and adds 3.00% AER (variable) on Instant Access savings, credit insights and custom spending categories, on top of everything in the free account. Monzo Perks, at £9 per month, includes everything in Extra plus partner perks worth over £300 a year (an annual Railcard, a weekly Greggs treat, a monthly Vue cinema ticket, an annual Uber One 3-month free trial and a YouTube Premium Lite trial), a 0.50% AER boost on Instant Access and Select Access savings, and a second credit score. Monzo Max, from £19 per month, raises the Instant Access savings rate to 3.50% AER (variable), lifts the outside-EEA cash withdrawal allowance to £600 per 30 days, and bundles worldwide travel insurance, worldwide phone insurance and UK and Europe breakdown cover. Extra, Perks and Max subscribers are also eligible for Billsback, which refunds up to £150 on at least 1,000 randomly selected eligible bills every month. In our test, upgrading and downgrading between plans via the app took under two minutes and the change applied immediately without any customer service call. Which one suits you better is settled in Chase vs Monzo.
The table below lines up every tier on the facts that actually change your monthly cost: the subscription price, both cash-withdrawal allowances, the Pots interest rate and Billsback eligibility.
| Monzo current account plan | Monthly price (GBP) | UK-EEA withdrawal limit (GBP per 30 days) | Outside-EEA withdrawal limit (GBP per 30 days) | Instant Access Pots rate (% AER) | Billsback eligible |
|---|---|---|---|---|---|
| Free | £0 | Unlimited if Fee Criteria met, else £400/30 days then 3% | £200/30 days, then 3% | 2.75% AER (variable) | No |
| Monzo Extra | £3 | Unlimited if Fee Criteria met, else £400/30 days then 3% | £200/30 days, then 3% | 3.00% AER (variable) | Yes |
| Monzo Perks | £9 | Unlimited if Fee Criteria met, else £400/30 days then 3% | £600/30 days, then 3% | 3.25% AER (variable) | Yes |
| Monzo Max | From £19 | Unlimited if Fee Criteria met, else £400/30 days then 3% | £600/30 days, then 3% | 3.50% AER (variable) | Yes |
One row needs a caveat rather than a clean number. Monzo's account-wide Fee Information document applies the Fee Criteria test to UK and EEA withdrawals on every plan without naming a tier, so that is the figure used above. Monzo Perks' and Monzo Max's own plan terms separately promise "no fees" on EEA withdrawals with no Fee Criteria condition attached, and Monzo's Extra plan terms do not mention cash withdrawals at all. Monzo hasn't reconciled these documents with each other, so a Perks or Max customer who hasn't checked whether they meet the Fee Criteria should confirm their actual UK withdrawal allowance in the app rather than assume either reading.
One charge that surprises new users: depositing cash requires visiting a PayPoint location, and Monzo charges £1 per deposit. That fee isn't hidden, but it's easy to miss in the sign-up flow. For anyone who routinely handles cash, this adds up over the course of a year. Sending money abroad also got cheaper this month: Monzo's international bank transfer fee changed on 1 November 2026, from a fixed amount of up to £9 plus 0% to 1.80% of the amount, to a fee that is now under £0.80 for most currencies and no more than £11 in the rest. We place the providers in context in this comparison: Monzo vs Starling.
Cards and payments
Every Monzo account comes with a Mastercard debit card, not a Visa, and not a credit card. Mastercard's global acceptance is excellent, and in practice the distinction rarely matters for everyday spending. The card is a hot coral colour on the free and Extra tiers, blue coral on Perks, and burnt coral on Max; Max customers can also opt for a metal card.
Apple Pay and Google Pay are both fully supported and set up directly inside the Monzo app. In our test, adding the card to Apple Wallet completed in under 30 seconds. Contactless payments via phone or watch work anywhere that accepts Mastercard contactless, which covers effectively all UK retailers and most European ones. There is no virtual card for online shopping separate from the physical card number, though some competitors have introduced this feature. Monzo's card number is static; you can't generate single-use numbers for privacy-sensitive purchases.
Sending money to another Monzo user via the app is instant and free using just their phone number or username. Splitting a bill works through a dedicated tab feature where you can divide a shared expense and chase participants through the app. International transfers to non-UK accounts are handled via Wise integration inside the Monzo app, meaning you use a third-party service with its own fee structure rather than a native Monzo international wire. If it isn't the right fit, we compared the strongest Wise alternatives.
Beyond the current account
A Monzo current account is also the entry point into a wider lending and investing range, and it's worth knowing what's actually available before you open the account expecting all of it on day one. Monzo offers an arranged overdraft of up to £2,000 to eligible customers, at a variable rate of 19%, 29% or 39% EAR depending on your credit score (representative APR 39.0%, variable); not everyone is offered one, but those who are get a clear in-app rate disclosure before borrowing a penny, and Monzo won't let a payment tip you into an unarranged overdraft. Personal loans go up to £35,000, with a representative APR of 10.0% on loans over £10,000 and up to £35,000, and 23.0% on loans up to £10,000. Monzo also offers investing (ready-made funds plus a Stocks and Shares ISA, a General Investment Account and a SIPP) through the app. One product to be careful about: Monzo Aura, an auto-investing cashback card with credit limits advertised up to £15,000, is marketed by Monzo itself as "coming soon" and is being rolled out gradually, so it's not yet something every applicant can sign up for outright.
- Arranged overdraft: up to £2,000, 19%/29%/39% EAR (variable) depending on credit score
- Personal loan: up to £35,000, representative APR 10.0% (over £10,000) or 23.0% (up to £10,000)
- Investing: ready-made funds, Stocks and Shares ISA, GIA and SIPP available in-app
- Monzo Aura: credit card with auto-invested cashback, up to £15,000 credit limit, Monzo's own site lists it as "coming soon"
Opening the account step by step
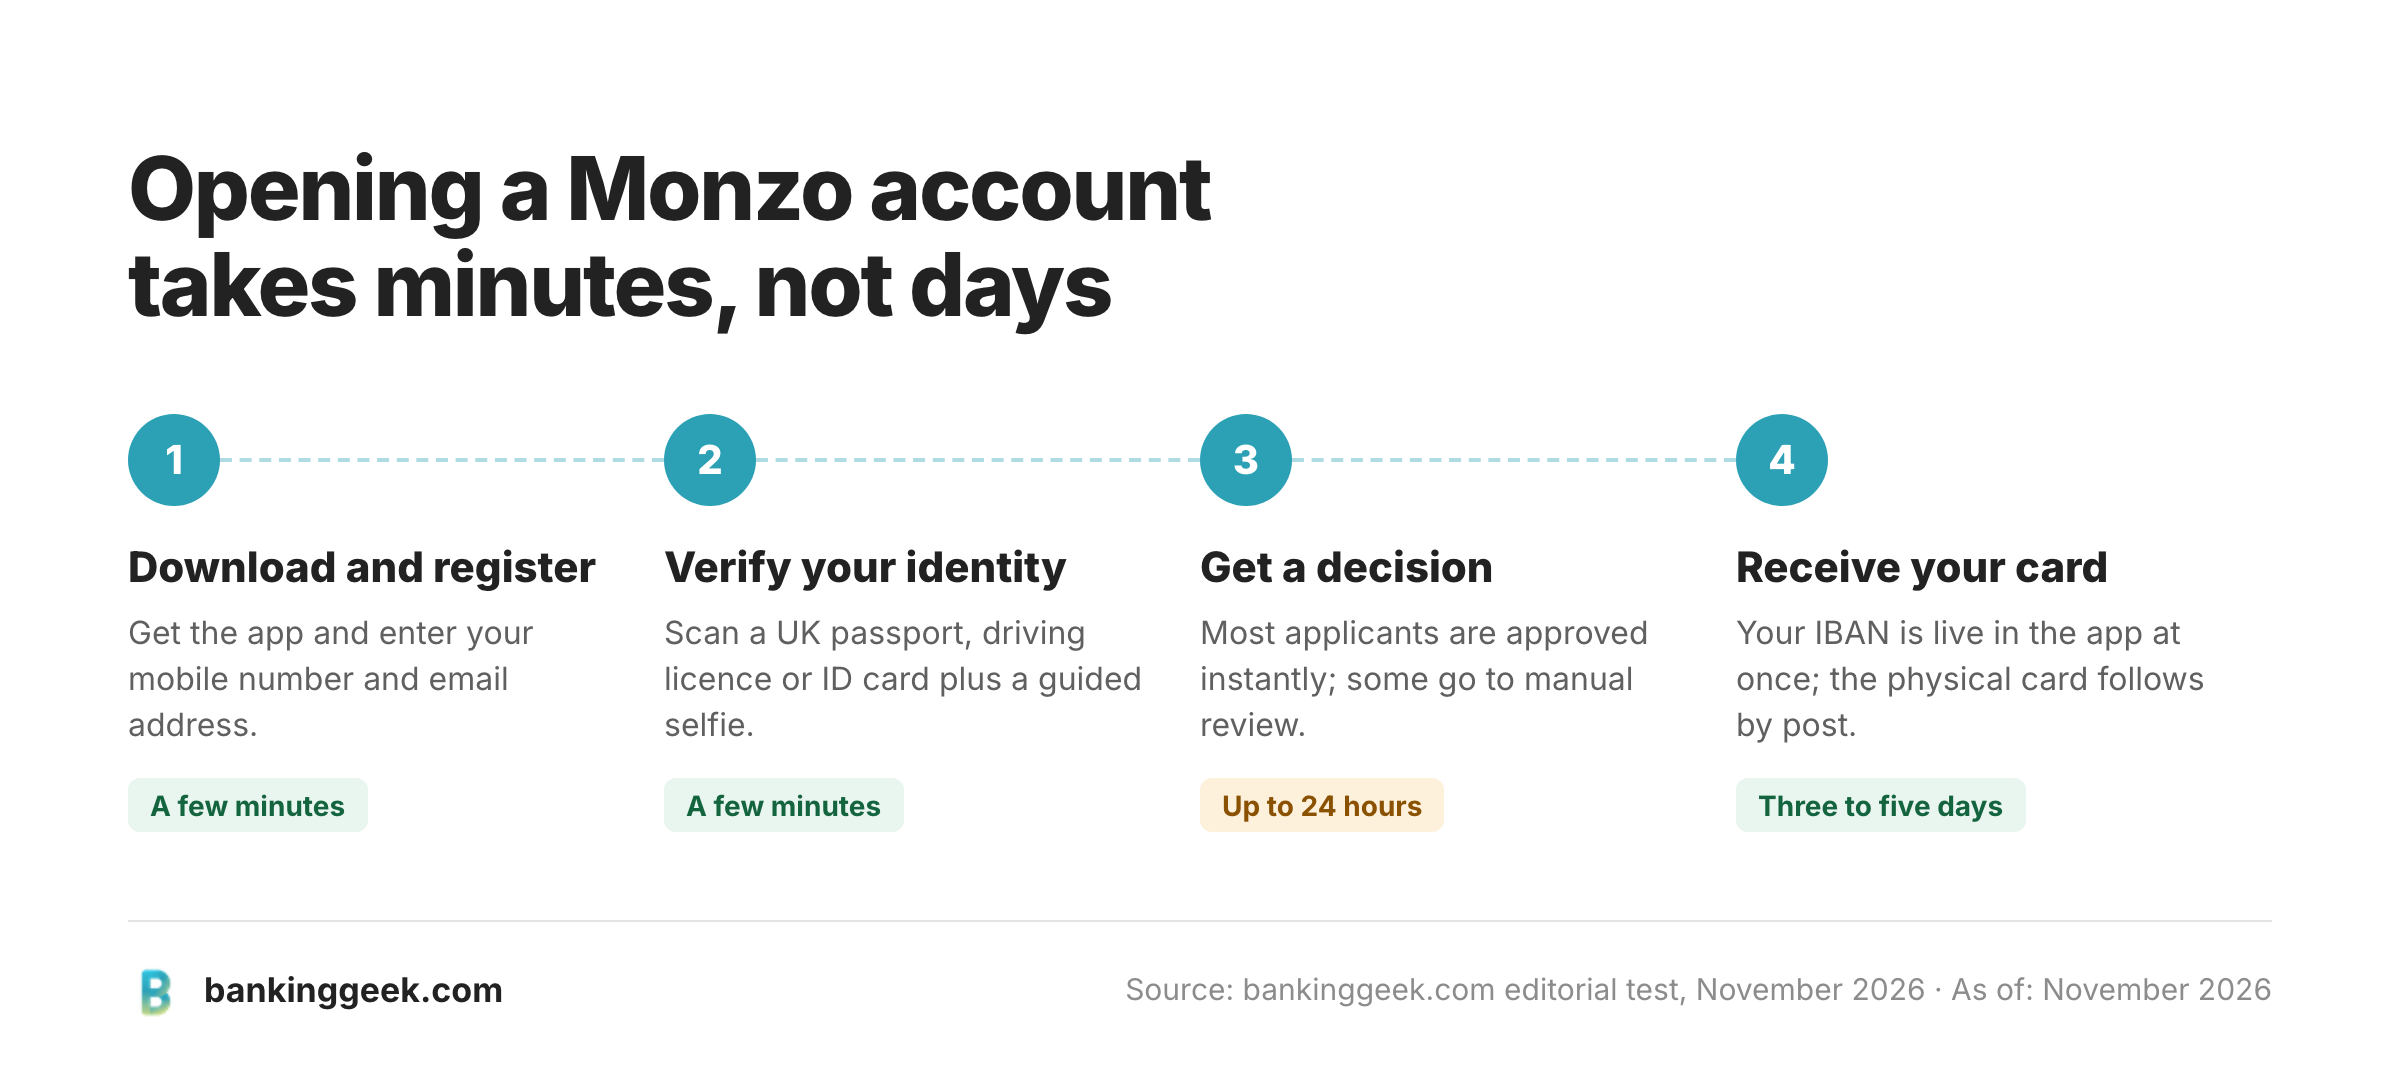
The process is fully online. Download the app from the App Store or Google Play, enter your mobile number and email address, then complete identity verification using your UK passport, driving licence, or national identity card. The app uses a guided selfie and document scan rather than posting documents or visiting a branch. Most applicants receive a decision within minutes, though occasionally the system flags an application for a manual review that can take up to 24 hours.
Once approved, a UK IBAN is issued immediately and visible in the app. Your debit card arrives by post within three to five working days. The IBAN uses the GB prefix, so international senders can locate the account as a UK sterling account without ambiguity. Sort code and account number are displayed alongside the IBAN for domestic transfers. You can set up direct debits and standing orders from day one without waiting for the physical card.
Monzo requires no minimum deposit to activate the account and no minimum monthly funding on the free tier. Some digital banks, notably Chase UK, require a minimum pay-in to access their interest rate; Monzo doesn't enforce this on the base plan. Closing the account is handled in the app as well; funds are transferred out and the account shuts within a few days, with no early-closure penalty. A broader selection is in this overview: Chase vs Revolut.
App, features and customer service
The Monzo app is consistently ranked at or near the top of the UK banking app charts on both iOS and Android. The interface groups transactions by merchant, shows a real-time balance that updates within seconds of a card payment, and provides a monthly summary broken down by category. Budgeting is built in rather than bolted on: you can set spending limits per category and receive a warning when you approach them.
Pots are the standby feature that Monzo users cite most. You can create multiple ring-fenced savings spaces inside the same account, name them, and optionally lock them until a set date. Round-up rules can move small amounts automatically after every transaction. None of this requires a third-party integration. For anyone who has tried to recreate this behaviour with a legacy bank using multiple sub-accounts and manual transfers, the difference in friction is considerable.
Customer service runs through in-app chat rather than a telephone line. Response times during UK business hours are generally fast; overnight and weekend waits can stretch to several hours. The help section is thorough and resolves a large proportion of common questions without needing to escalate to a human agent. Monzo has introduced a telephone number for certain urgent situations such as card fraud, but routine queries are expected to go through chat. This is a reasonable model for a digital bank, though it does mean that customers who prefer a voice conversation will find the experience less familiar.
Reputation and real customer experience
Monzo holds a strong reputation on Trustpilot and consistently appears near the top of Which? surveys for bank customer satisfaction. Recurring praise focuses on the instant notifications, the pots feature, and the ease of disputing a transaction. Users who have had to deal with fraud report that blocking a card and requesting a replacement through the app takes under a minute, which compares well with the phone hold times reported at some high-street banks.
Recurring complaints fall into identifiable themes. Account freezes and closures are the most cited frustration. Monzo, like all UK banks, is obligated to monitor transactions and freeze accounts on suspicion of financial crime; critics argue the automated triggers are too sensitive and that restoring access takes too long when the freeze is a false positive. A second theme is the lack of phone support for non-urgent matters: customers who aren't comfortable with chat find the resolution process slow. A third theme is overdraft availability: not all applicants are offered an arranged overdraft, and those who are report interest rates that are high relative to traditional bank overdraft products.
The overall picture is of a bank that performs very well for its core use case, namely day-to-day spending management for app-comfortable users, and less well at the edges: complex financial situations, high-cash lifestyles, and customers who need human contact for routine banking questions.
Verdict: open it or look elsewhere
Open a Monzo current account without question if your priority is visibility over your spending. The combination of instant notifications, categorical breakdowns, and pots makes it one of the most practical budgeting environments available on a free account in the UK. The Mastercard debit card, Apple Pay, Google Pay support, and fee-free foreign card spending with no monthly cap make it a sensible travel companion as well; just keep the cash-withdrawal allowances in mind if you rely on ATMs abroad.
Consider the paid tiers only if the interest rate on Extra, Perks or Max actually beats what a separate savings account would give you on the same balance, and only if you value the bundled perks or insurance. From £19 per month, Monzo Max competes with Nationwide FlexPlus and similar packaged accounts; do the maths on whether you would buy the travel insurance independently before assuming the bundle saves money.
Look elsewhere if you need physical branches, cheque deposit, a CHAPS transfer facility, or an overdraft as a core feature. Chase UK currently offers a higher cashback rate on spending for new customers; Starling Bank has a broadly similar feature set with a slightly different design philosophy and a longer track record on the business banking side. Revolut provides more aggressive international money transfer rates for frequent travellers, though its regulatory status in the UK differs from Monzo's full bank licence. The free Monzo account is hard to beat as a primary UK current account for most salaried employees who manage their finances by phone. That's a narrow but accurate claim, and for that audience the product earns its reputation.
How safe is Monzo Current Account?
Monzo Current Account vs alternatives
A direct comparison of the key conditions against the strongest competitors in the market.
 |  |  |  | |
| Rating | 5.0 /5 | 5.0 /5 | 5.0 /5 | 4.0 /5 |
| Monthly fee | £0/month | £0/month | £0/month | £0/month (Standard Plan) |
| Debit card | ✓ | ✓ | ✓ | ✓ |
| Credit card | ✗ | ✗ | ✓ | ✗ |
| Apple Pay | ✓ | ✓ | ✓ | ✓ |
| Google Pay | ✓ | ✓ | ✓ | ✓ |
| Cash withdrawal abroad | Free up to £200/30 days; then 3% (Perks/Max: £600/30 days) | Free (no Starling fees) | No fee; up to £1,500/month abroad | Free up to £200/month; then 2% |
| Online account opening | ✓ | ✓ | ✓ | ✓ |
| Deposit protection | £120,000 | £120,000 | £120,000 | £120,000 |
| iOS app | ✓ | ✓ | ✓ | ✓ |
| Branches | ✗ | ✗ | ✗ | ✗ |
How we rate
More comparisons
- The Best PayPal Alternatives 2026 →
- Wise vs Monzo: Which Is Better in 2026? →
- Chase vs Monzo: Which Is Better in 2026? →
- Monzo vs Chase: Which Is Better in 2026? →
- Revolut vs Monzo: Which Is Better in 2026? →
- Monzo vs Starling: Which Is Better in 2026? →
- Best Monzo Current Account Alternatives 2026: 6 Top Options →
About the author
Frequently asked questions
Yes. Monzo Bank Limited holds a full UK banking licence and is authorised by the Prudential Regulation Authority (PRA) and regulated by both the PRA and the Financial Conduct Authority (FCA). Your deposits are protected by the FSCS up to £120,000.
The standard Monzo current account has no monthly fee and no minimum balance. Paid tiers (Monzo Extra, Monzo Perks and Monzo Max) charge a monthly subscription for additional features such as higher savings interest and (on Max) travel insurance. Cash deposits via PayPoint carry a fee.
On the free account, Monzo lets you spend on your card overseas at the Mastercard exchange rate with no transaction fee. ATM withdrawals abroad are free up to a monthly limit; withdrawals above that limit incur a small percentage charge. Paid tiers offer higher or unlimited fee-free overseas ATM use.
Monzo offers arranged overdrafts to eligible customers subject to a credit check, but approval is not guaranteed. The interest rate and daily cost are shown clearly in the app before you use the facility. Monzo does not permit unarranged overdraft borrowing -- payments that would take you over your limit are declined.
Yes. Monzo is a full participant in the Current Account Switch Service (CASS). The switch takes seven working days and is free. Your direct debits, standing orders and incoming salary are moved automatically, and payments to your old account are forwarded for at least three years.
All three are digital-only UK banks with free current accounts and strong apps. Starling is noted for its Spaces and business banking. Chase pays cashback on card spending. Monzo stands out for its budgeting pots, salary sorter, and the breadth of its paid-tier ecosystem. The best choice depends on whether you prioritise interest, cashback or budgeting tools.