
Atom Bank Instant Saver: review 2026
Last updated: 20.10.2026
Contents
Summary
The Atom Bank Instant Saver is a strong choice for UK savers who are comfortable managing their money entirely through an app. It offers a competitive easy-access rate of around 2.50% AER on the standard Instant Saver, rising to 3.49% AER on the Instant Saver Reward tier if you make no withdrawals in a month. Deposits up to 120,000 GBP per person are covered by the FSCS, making it well suited to anyone who wants a straightforward, branch-free savings account with a reputable digital bank.
Pros
- Competitive easy-access rate of around 2.50% AER with no conditions on the standard tier
- Instant Saver Reward pays 3.49% AER in any month without withdrawals
- FSCS protection up to 120,000 GBP per person per bank
- Consistently well-rated app on both iOS and Android
- Fully online opening process, typically completed in minutes
Cons
- App-only model, no branches or telephone savings line
- The higher Reward rate is forfeited if you make even one withdrawal in the month
- Variable rate can be changed by the bank at short notice
- No current account or debit card, so Atom Bank cannot act as a primary bank
Key facts
| Interest on savings account | ca. 2.50% AER easy access (Instant Saver); Instant Saver Reward: 3.49% AER with no withdrawals, 2.00% AER Withdrawal rate otherwise |
| Deposit protection | £120,000 |
| Online account opening | ✓ |
| Welcome bonus | – |
| Joint account | – |
| Overdraft interest rate | – |
| Savings account | – |
| Rating | 4.0 /5 |
Interest rate comparison
The effective annual rate compared directly with the alternatives.
A closer look

Overview: what the Atom Bank Instant Saver is, and who it suits
Atom Bank launched in 2016 as the UK's first app-only bank, and its Instant Saver sits at the centre of its retail deposit range. The account's designed for straightforward, no-friction saving: you deposit money, it earns interest, and you can withdraw any time without penalty. There are no branches, no telephone savings line, and no paperwork sent through the post. Everything happens inside the Atom app, which is available on iOS and Android.
A dedicated article goes into the detail: Everything You Need to Know About Checking Accounts.
The Instant Saver targets savers who are already comfortable managing money on a smartphone. That includes people building an emergency fund, those parking surplus cash between larger investments, and anyone frustrated by the near-zero rates still offered by many high-street banks on their easy-access accounts. The app-first model also appeals to savers who value simplicity: one app, one rate, no product alphabet soup. Which accounts else are worth a look is covered here: Best joint savings account.
Savers who prefer face-to-face service, those who need to pay in cash or cheques, or anyone whose household shares a savings pot and needs joint account functionality will find Atom's current setup limiting, so this account isn't the right fit for them. The Instant Saver is also less compelling for savers who can lock money away for one to five years, because Atom's own fixed-term bonds typically pay meaningfully higher rates than the easy-access product.
The interest rate explained: base, reward, and how it is paid
Atom Bank publishes two rates for the Instant Saver. The standard rate sits at approximately 2.50% AER on an easy-access basis; this is the rate applied by default and changes at Atom's discretion, so it's variable. AER (Annual Equivalent Rate) is the UK's standardised figure that accounts for compounding, making comparisons with other providers straightforward. We place the providers in context in this comparison: Best children's savings account.
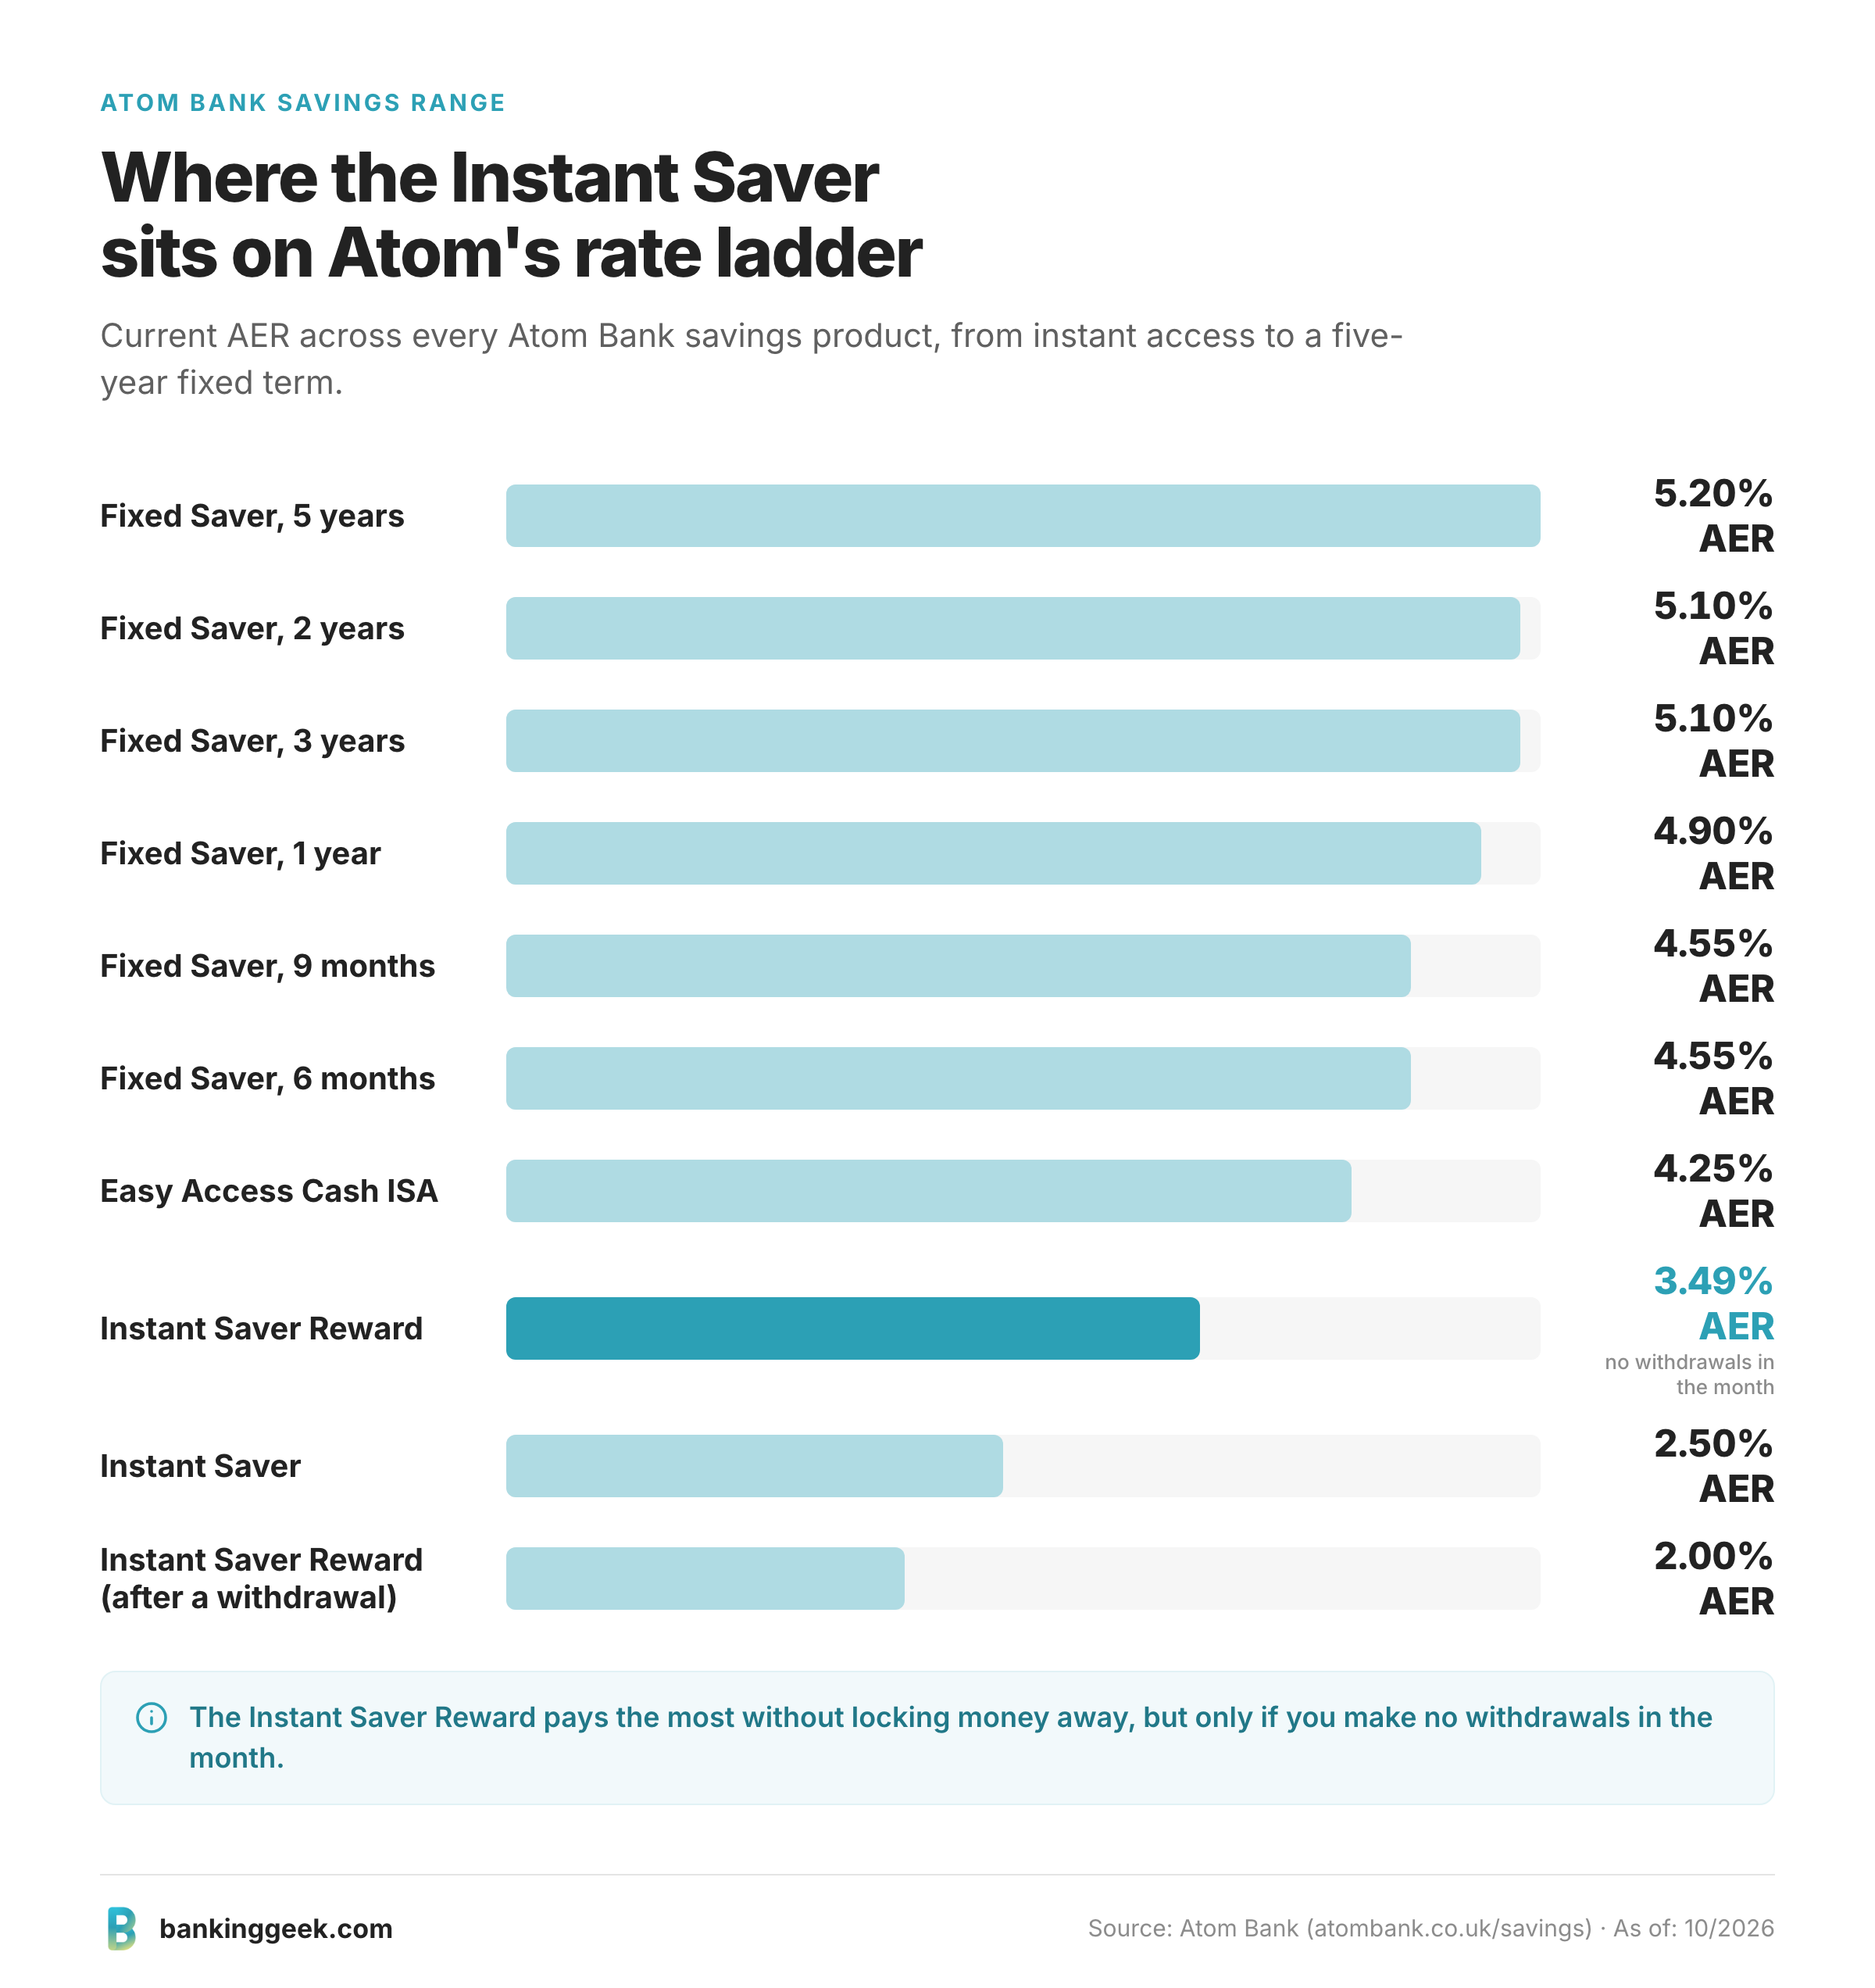
Alongside the standard rate, Atom runs what it calls the Instant Saver Reward rate of 3.49% AER. The key condition: you make no withdrawals during the relevant period. In our test, the mechanics were clear enough inside the app, though the distinction between the two rates is worth reading carefully before you assume you're automatically earning the higher figure. If you withdraw even once, the reward rate switches to Atom's dedicated Withdrawal rate, currently 2.00% AER, for that monthly interest period, before moving back to the Reward rate the following month. Atom gives at least 14 days' notice before cutting the Reward rate, so a reduction won't catch you out without warning. You can hold only one Instant Saver Reward account, and it must be a sole account rather than a joint one, alongside one Instant Saver.
Interest on the Instant Saver accrues daily and is credited to the account monthly. That means your balance grows incrementally rather than in a single year-end lump, which is useful for savers who want to see progress. Atom caps combined balances across the Instant Saver, Instant Saver Reward and Holding Accounts at a Maximum Balance Limit of 100,000 pounds, which is comfortably above what most retail savers hold in easy-access cash. Both the standard and reward rates are subject to change, and Atom has moved them multiple times in step with Bank of England base rate shifts.
There's no introductory bonus that expires after 12 months, a common trap with some competitors.
Atom's wider savings range gives useful context for where the Instant Saver sits. The table below shows the current AER for every product Atom offers, from instant access and a Cash ISA to a five-year fixed term.
| Product | AER | Minimum deposit | Access |
|---|---|---|---|
| Instant Saver | 2.50% (variable) | £0 | Instant, unlimited withdrawals |
| Instant Saver Reward | 3.49% (variable), drops to 2.00% in a withdrawal month | £0 | Instant, but withdrawing cuts the rate for that monthly period |
| Easy Access Cash ISA | 4.25% (variable) | £0 | Instant, but withdrawn money needs fresh ISA allowance to replace |
| Fixed Saver, 6 months | 4.55% (fixed) | £50 | Locked until maturity |
| Fixed Saver, 9 months | 4.55% (fixed) | £50 | Locked until maturity |
| Fixed Saver, 1 year | 4.90% (fixed) | £50 | Locked until maturity |
| Fixed Saver, 2 years | 5.10% (fixed) | £50 | Locked until maturity |
| Fixed Saver, 3 years | 5.10% (fixed) | £50 | Locked until maturity |
| Fixed Saver, 5 years | 5.20% (fixed) | £50 | Locked until maturity |
The variable nature of the Instant Saver rate is the primary trade-off against a fixed-term bond. As the table shows, Atom's own one-year Fixed Saver pays 4.90% AER, well above the Instant Saver's 2.50% standard rate, and its five-year Fixed Saver reaches 5.20%. If liquidity genuinely isn't required, the fixed range deserves consideration before defaulting to the easy-access product.
Tax on savings interest in the UK: what to expect
Interest earned on the Atom Bank Instant Saver is treated as savings income and falls within the UK's standard Personal Savings Allowance framework. Basic-rate taxpayers (20%) receive a Personal Savings Allowance of 1,000 pounds per tax year; higher-rate taxpayers (40%) receive 500 pounds. Additional-rate taxpayers (45%) receive no allowance at all and pay tax on every pound of interest earned.
Atom Bank doesn't deduct tax at source. Interest is paid gross into your account, and you're responsible for declaring any amount above your allowance via Self Assessment or by contacting HMRC directly if you don't normally complete a tax return. For most basic-rate savers with modest balances the allowance will cover the full year's interest, but higher earners or those with significant deposits across multiple accounts should keep records.
The Financial Conduct Authority regulates Atom Bank as a UK-authorised bank, and interest income reported for tax purposes should match the annual interest statement Atom provides through the app. That statement is available on demand rather than posted, another reminder that the account is built entirely around digital interaction.
Opening the account: step by step
The application is entirely app-based and takes most applicants under ten minutes to complete, assuming documents are ready. You download the Atom app, enter a mobile number, verify it by SMS, and then begin the identity check. Atom uses automated document scanning: you photograph a UK passport or driving licence, then complete a short facial recognition step. The process follows FCA-compliant electronic verification standards. Atom runs only a soft credit check when you apply, so opening the account doesn't show up as a search on your credit file or affect your credit score.
Once identity is confirmed, you choose a six-digit PIN and set up biometric login if your device supports it. Funding the account is done by bank transfer from an existing UK account; the connected account must be a UK personal current account registered in your own name, since Atom doesn't accept transfers from business current accounts. Atom doesn't accept cash deposits or cheque payments. The IBAN format for incoming transfers is a standard UK sort code and account number rather than an international IBAN string, as Atom holds a full UK banking licence.
There's no lock-in period for the Instant Saver. You can transfer money out at any time by initiating a withdrawal inside the app back to a nominated UK bank account. Atom doesn't impose notice periods on the Instant Saver, which distinguishes it from some competitive products that label themselves easy-access but actually require 30 to 95 days notice. Withdrawals typically clear on the same working day when initiated before the published cut-off time.
Safety: FSCS protection and who stands behind Atom Bank
Atom Bank is a fully authorised UK bank regulated by both the Prudential Regulation Authority and the Financial Conduct Authority. Deposits are protected by the Financial Services Compensation Scheme up to 120,000 pounds per person, per authorised firm. The 120,000 pound limit applies to your combined eligible deposits at Atom, not per account, so savers with both an Instant Saver and a fixed bond should keep the aggregate below this threshold or accept that the surplus sits outside the guarantee.
The FSCS is the UK's statutory deposit protection scheme. It's funded by levies on authorised financial services firms and backed by HM Treasury as a lender of last resort. In the event of a bank failure, FSCS aims to pay protected deposits within seven business days, though complex cases can take longer. This is broadly comparable to the EU's Deposit Guarantee Schemes Directive framework, which mandates the same seven-day target in member states.
Atom's ownership structure includes significant backing from BBVA, the Spanish banking group, which has backed Atom since before its 2016 public launch, first investing in 2015 and increasing its holding to around 39% in 2018. BBVA, Toscafund and Infinity Investment Partners contributed to a further £100 million funding round in November 2023. That long-standing institutional ownership provides a degree of financial reassurance beyond what a purely venture-backed startup might offer, though it's the FSCS cover, not corporate parentage, that legally protects retail savers.
Reputation and real customer experience
Atom Bank consistently scores well in independent app store reviews, with ratings above 4.5 on both the Apple App Store and Google Play at the time of writing. The feedback that recurs most often centres on three themes: the speed of account opening, the clarity of the interest rate display inside the app, and the reliability of the withdrawal process. Savers frequently comment that transfers out of the account arrive in their nominated account on the same day, which matters when the account's used as a liquid emergency reserve.
Recurring complaints follow a predictable pattern for an app-only bank. Customer support is limited to in-app messaging and email; there's no telephone number for savings customers. Response times via messaging are generally adequate during business hours, though they're slower at weekends. Some users express frustration that the reward rate requires zero withdrawals, discovering this condition only after making a routine transfer. A smaller number of complaints relate to the verification step during opening, particularly for customers whose passport or driving licence has minor damage that confuses the automated scanner.
On Trustpilot, Atom holds a 4.8 TrustScore across more than 22,000 reviews, placing it in the "Excellent" band, with a significant majority of reviewers giving four or five stars. Feefo, a second independent review platform, rates Atom "Exceptional": a 98% customer recommendation rate and 4.8 out of 5 for both service and product across more than 20,000 reviews, so the Trustpilot result isn't an outlier. Critical reviews tend to focus on the limited product range rather than operational failure: Atom doesn't offer a current account, credit cards, or personal loans, so savers who want to consolidate their finances in one place will always need a separate main bank. This isn't a flaw in the Instant Saver itself, but it does shape who finds the account genuinely convenient versus those for whom it remains a second relationship to manage.
Verdict: open it, or look elsewhere
The Atom Bank Instant Saver is a safe, well-run easy-access account, though it's no longer a rate leader. The 2.50% AER standard rate still comfortably beats what most UK high-street banks pay on easy access, where rates commonly sit under 2%, and the 3.49% AER reward rate adds a genuine incentive if you can keep withdrawals to zero in a given period. Set against the wider standalone savings market, though, Atom has fallen behind: independent savings-rate trackers place the Instant Saver below both the current market-average easy-access rate and UK inflation as of October 2026, and several challenger providers now pay more on a comparable no-notice product, so it's worth comparing Atom against the current best-buy tables before you commit. FSCS protection up to 120,000 pounds means there's no meaningful safety disadvantage compared to any other UK-authorised bank.
Open this account if you want a digitally clean, low-friction home for liquid savings and you're comfortable with an app-only experience. It works particularly well as a companion to a high-street current account: your day-to-day spending stays where it is, while idle cash earns a proper rate rather than sitting at 0.1% in a current account buffer. The monthly interest credit is also a practical feature for savers who like to track growth in real time.
Look elsewhere if you can't commit to the app-only model, if you need to pay in cash or cheques, or if you want a joint account.
Look elsewhere too if a market-leading rate is your only priority, for the reasons set out above. Look elsewhere also if your time horizon is fixed: Atom's own term deposits will almost certainly pay more for money you can genuinely lock away for 12 months or longer. And if your total savings across all accounts exceed 120,000 pounds, you'll need to spread across multiple FSCS-covered institutions regardless of which easy-access account you choose, so the Instant Saver becomes one part of a wider structure rather than a single destination.
How safe is Atom Bank Instant Saver?
Atom Bank Instant Saver vs alternatives
A direct comparison of the key conditions against the strongest competitors in the market.
 |  |  |  | |
| Rating | 4.0 /5 | 4.0 /5 | 4.0 /5 | 4.0 /5 |
| Interest on savings account | ca. 2.50% AER easy access (Instant Saver); Instant Saver Reward: 3.49% AER with no withdrawals, 2.00% AER Withdrawal rate otherwise | 2.25% AER variable (Boost: 4.50% AER for 12 months for new customers, requires a Chase current account) | ca. 3.50% AER easy access (Promo Boost: up to 5.01% AER for 6 months for new customers) | ca. 3.75% AER easy access (incl. 0.49% bonus for 12 months) |
| Deposit protection | £120,000 | £120,000 | £120,000 | £120,000 |
| Online account opening | ✓ | ✓ | ✓ | ✓ |
| Welcome bonus | – | ✓ | – | – |
| Joint account | – | ✗ | – | ✓ |
| Overdraft interest rate | – | ✗ | – | – |
| Savings account | – | ✓ | – | – |
How we rate
About the author
Frequently asked questions
The account is available to UK residents aged 18 and over. You will need a valid UK photo ID and a smartphone capable of running the Atom Bank app. Joint accounts are not available on this product.
There are no monthly fees, no opening fees, and no withdrawal charges on the Instant Saver. The only cost of withdrawing is that you lose the Reward rate for that calendar month if you are on the higher-rate tier.
Yes. Atom Bank holds a full UK banking licence and your deposits are covered by the FSCS up to 120,000 GBP per person per bank. This protection is backed by the UK government and applies automatically without any registration.
Download the Atom Bank app on iOS or Android, enter your personal details and National Insurance number, then complete a biometric ID check using your phone camera and a valid UK photo ID. Most applicants are verified within minutes and can fund the account immediately by bank transfer.
Atom Bank is authorised by the PRA and regulated by the FCA and PRA, the two main UK financial regulators. It has operated since 2014 and holds customer deposits under FSCS protection. The app uses biometric authentication and two-factor security for account access.
Interest counts toward your Personal Savings Allowance: 1,000 GBP per tax year for basic-rate taxpayers and 500 GBP for higher-rate taxpayers. Interest above your allowance is taxed at your marginal income tax rate. Atom reports interest to HMRC automatically, so for most PAYE earners no additional paperwork is needed.