Bank of Scotland Business Bank Account: review 2026
Last updated: 08.10.2026
Contents
Summary
The Bank of Scotland Business Bank Account is a solid traditional option for UK small businesses and sole traders who value branch access, a recognisable name and a year of free banking to get started. With a £10 monthly fee kicking in after month twelve and no Apple Pay or Google Pay support on the standard debit card, it suits established businesses more than those seeking a lean digital-first setup. FSCS protection covers up to £120,000 per person per bank, giving straightforward peace of mind on deposits.
Pros
- Free banking for the first 12 months for new businesses
- current opening offer of a £200 boost, six months of Xero free and a £200 Amazon gift card (ends 15 October)
- FSCS deposit protection up to £120,000 per person per bank
- Account manageable online, via mobile app, in branch or by phone
- Visa Business Debit Card included with contactless payments
Cons
- Monthly fee of £10 applies after the free introductory year
- Apple Pay and Google Pay not supported on the standard business debit card
- Foreign cash withdrawals attract a 2.75% non-sterling transaction fee plus a 1.5% cash fee
- No virtual card option on the standard business account
Key facts
| Monthly fee | Free for 12 months, then £10/month |
| Debit card | ✓ |
| Credit card | ✓ |
| Virtual credit cards | ✗ |
| Free cash withdrawal | ✗ |
| Number of sub-accounts | plan dependent |
| Online banking users | Several |
| Electronic transfers | ✓ |
| Apple Pay | ✗ |
| Google Pay | ✗ |
| 3D Secure for online payments | ✓ |
| Deposit protection | £120,000 |
| Rating | 3.5 /5 |
Strengths in detail
How well the provider covers the most important areas.
A closer look
Overview: who this account is for, and who should skip it
Bank of Scotland has been serving Scottish businesses since 1695, and the current Business Bank Account carries that long institutional heritage into a fairly conventional UK business current account. It sits within the Lloyds Banking Group alongside Halifax and Lloyds Bank. That means broad branch coverage across Scotland and significant parts of England, a mature online banking platform, and a well-staffed telephone service.
For sole traders and limited companies that value face-to-face banking, a recognisable name on their business statement, and a free-banking window while cash flow is still building, the account has genuine appeal.
The account's open to businesses with an annual turnover of £25m or less. Applicants must be at least 18, a UK resident with a UK mobile number, and either a sole trader or a company director trading from a UK address. The 12-month fee-free period is worth checking carefully, though: it only applies if this is the business's first current account with Bank of Scotland, not to every new application.
There's a current opening offer for a qualifying new account too, a £200 boost, six months of Xero free, and a £200 Amazon gift card, if the account is opened by 15 October, and it's worth reading the exact mechanics before you apply: a minimum card spend and two direct debits unlock the £200, and the Amazon card follows a seventh Xero payment. Businesses that already bank with Bank of Scotland personally may also find the relationship helpful for credit conversations further down the line. A broader selection is in this overview: Best packaged bank account.
It's worth being just as direct about who this account doesn't suit. If you regularly pay suppliers or receive client funds in currencies other than sterling, the 2.75% non-sterling transaction fee on card payments will add up quickly, and the international and correspondent-bank-fee schedule for wire payments is more detailed than most challenger banks publish. There aren't any virtual card numbers for subscription or vendor-spend control either, and the app can't upload multiple payments as a single CSV batch, which is a genuine friction point if you're paying several suppliers at once. Very small businesses with minimal transaction volumes should compare the post-year-one £10 monthly fee against zero-fee digital alternatives before committing. More providers are listed here: Best Current Account in the UK.
Real costs and hidden fees in detail
The headline's accurate as far as it goes: no monthly fee for the first 12 months, provided this is the business's first current account with the bank. After that, the standard tariff is £10 per month (£120 a year). That's not the most expensive business account on the UK market, but it's meaningfully higher than the growing cluster of fee-free challengers.
New customers who open a qualifying account by 15 October can currently claim a £200 boost, six months of Xero Business Edition free, and a £200 Amazon gift card. The £200 boost needs £100 spent on the Business Debit Card plus two direct debits set up by 31 December, and the Amazon gift card follows the seventh Xero subscription payment. How it stacks up against the rest of the market is shown here: Best bank account UK.
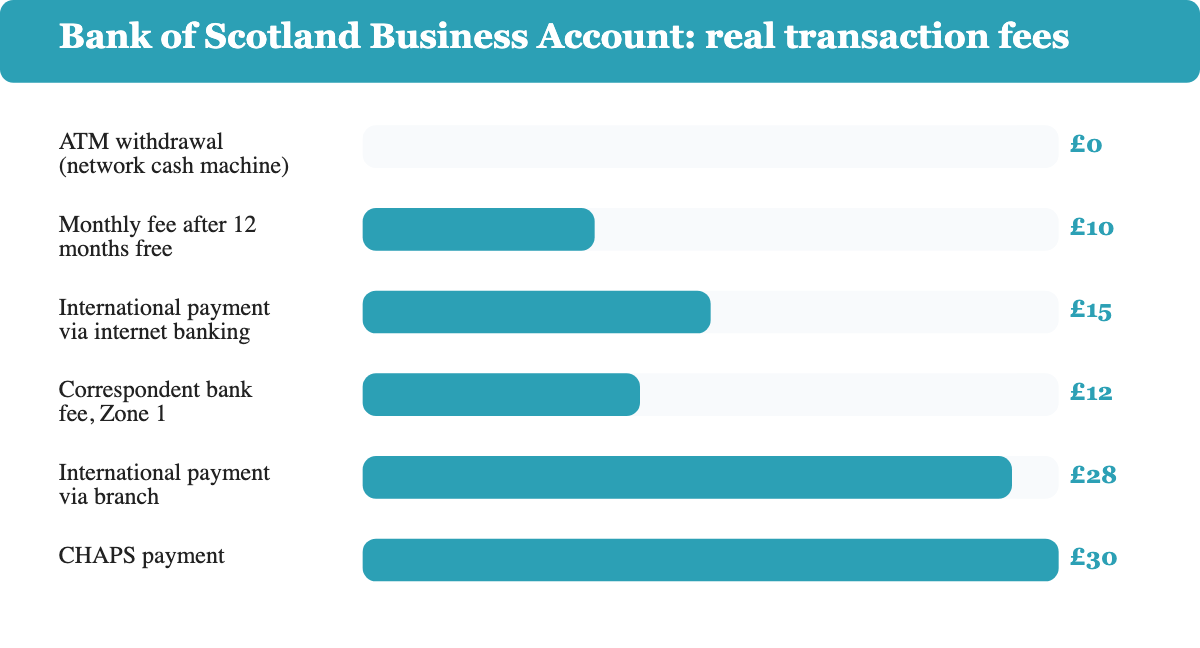
Beyond the monthly fee, the transaction tariff is specific rather than vague. Electronic payments in and out, including Direct Debits, Standing Orders and Faster Payments, don't cost extra. Cash paid in or out costs £0.85 per £100 at an Immediate Deposit Machine, or £1.60 per £100 over the counter; cheques cost £0.85 via an Immediate Deposit Machine or the mobile app, or £1.20 over the counter, and you can pay them in through the app up to a daily limit of £20,000. BACS costs £5.50 per file submission plus £0.15 per item, and CHAPS payments cost £30 each. ATM withdrawals using the Business Debit Card at a Bank of Scotland, Lloyds Bank or Halifax cash machine aren't charged at all. International payments cost £15 when sent via internet banking or £28 via branch; non-urgent Euro payments through SEPA Credit Transfer cost £5. A correspondent bank fee applies on top for some destinations: £12 for Zone 1 (the USA, Canada, Switzerland, Monaco, San Marino, Jersey, Guernsey and the Isle of Man) and £20 for the rest of the world. Receiving money from abroad costs £2 for amounts up to £100 or £7 above that, with no charge for euro payments arriving from the EEA.
Every card payment made in a currency other than sterling also attracts a separate 2.75% non-sterling transaction fee. For a business spending £1,000 a month on, say, US software subscriptions, that's an extra £27.50 a month, or £330 a year, and there's no virtual-card workaround since the standard account doesn't offer virtual card numbers. On the lending side, eligible businesses can apply for up to £25,000 across a Business Overdraft and/or Business Credit Card, with an instant online decision once the current account itself is open. Lending's a separate application though, and it's subject to status.
Cards and payments
Every Business Bank Account comes with a Visa Business Debit Card that supports contactless payments. 3D Secure is active for online card purchases, which satisfies most e-commerce payment gateways and gives the business chargeback protection on disputed transactions.
You can add additional cardholders under the multi-user online banking setup, useful if more than one director or employee needs spending access.
Unlike some older-generation business accounts, both Apple Pay and Google Pay work with the Business Debit Card. The quickest way to set either up is through the Business Banking app: open the app, select Cards, choose the debit card, then add it to Apple Wallet or Google Wallet and confirm the terms. You can also add Apple Pay directly from the Wallet app on a compatible iPhone, iPad, Mac or Apple Watch. For business owners who've grown accustomed to tapping their phone for purchases, this removes what used to be a day-to-day friction point on traditional bank accounts. A Visa Business Credit Card is available separately, with its own credit assessment and its own terms, so review that one independently.
The real limitation sits elsewhere. There aren't any virtual card numbers on the standard plan, so businesses that use virtual cards for subscription management, vendor spend controls, or online security will need a specialist fintech provider alongside this account. App Store reviewers also flag that you can't upload payments as a single CSV batch, so paying several suppliers at once still means submitting them one by one rather than in bulk. Contactless limits follow UK standard rules, and chip-and-PIN's still there for every terminal transaction.
Opening the account step by step
Applications for new businesses can be started online. Before applying, check the basic eligibility: at least 18 years old, a UK resident with a UK mobile number, and the business trading from a UK address with turnover of £25m or less. Limited companies face a further check. The business must be registered in the UK, have been on the Companies House register for at least four days, show an "active" status, and have had no changes made to that register in the past four days. Sole traders typically find the process more straightforward; limited companies with multiple directors should expect to provide identity and address documentation for each individual named on the account. If you're still shopping around, start here: Best business account for sole traders in the UK.
The IBAN for UK accounts follows the GB format, with Bank of Scotland's own sort codes sitting within the Lloyds Banking Group range. Most UK payment processors and accounting integrations handle GB IBANs without issue. European counterparts sending euro payments will route via SWIFT, so it's worth confirming your BIC with the bank at account opening rather than discovering it mid-transaction.
Borrowing's handled as a separate step. Once the current account itself is set up, eligible businesses can apply online for up to £25,000 across a Business Overdraft and/or Business Credit Card and get an instant decision, though lending remains subject to status and isn't guaranteed. Bank of Scotland doesn't publish an exact account-opening turnaround time, so it's worth treating any specific day-count you see elsewhere with caution. A straightforward sole trader application with documents ready is generally the fastest path, while limited companies with multiple directors or a recently changed Companies House filing should expect extra verification steps.
App, features and customer service quality
Bank of Scotland's Business Banking app is available on iOS and Android, works around the clock, and supports fingerprint or Face ID login on compatible devices. Day to day it covers balance checks, payment initiation, payee management and statement downloads. It also goes further than many traditional banks' apps on raw limits: you can pay cheques in via the app up to £20,000 a day, and make payments of up to £250,000 a day through it. The app links to personal accounts held with the same group too, which can simplify oversight for business owners who also bank personally with Halifax or Lloyds.
Multi-user online banking lets the business set up additional users with defined payment limits and access levels. That's meaningful for small businesses with a bookkeeper or operations manager who needs read access or limited payment authority without full account control. The permissions model isn't as granular as some fintech alternatives, but it covers the most common delegation scenarios.
The one notable app gap, confirmed by App Store reviewers rather than marketing copy, is bulk payment handling: there's no CSV upload for paying several suppliers in one batch. Telephone support is available during extended business hours, and the Scottish branch network provides in-person access for businesses that want to discuss lending, overdrafts, or account queries face to face. Dedicated relationship managers are assigned at higher relationship tiers; at the standard business account level, service is handled through the general business banking phone line.
Reputation and real customer experience
The honest picture here's a split one, and it's more useful to give the real numbers than a vague summary. On Trustpilot, Bank of Scotland's overall rating sits at 1.5 out of 5 from over 1,100 reviews, a genuinely poor score. The recurring complaints are long telephone wait times, an unhelpful virtual-agent chatbot, payments being blocked or declined without clear explanation, and local branch closures.
Against that, the Business Banking app itself holds a 4.8-out-of-5 rating from more than 9,000 App Store reviews, a far better figure that points to a real gap between "the app works well" and "getting help from a human is slow." A business weighing this account should read that as two separate signals rather than one blended reputation score.
As part of a regulatory requirement, an independent survey of around 1,200 customers of each of the UK's 17 largest business current account providers asks whether they'd recommend their provider to other small and medium-sized enterprises; the results are published as the Financial Conduct Authority's Service Quality Information for business current accounts. Bank of Scotland's results sit in that published dataset alongside its peers, and the bank's own Business Banking site links directly to the regulator's full results rather than only quoting a favourable headline figure. That's worth checking directly if service quality is what decides it for you.
The bank's complaints handling, as reported to the Financial Conduct Authority, is publicly disclosed in semi-annual data. There's no published evidence of systemic service failures beyond the patterns visible in the Trustpilot reviews above, and the account's long track record provides a level of operational stability that newer providers haven't yet demonstrated across a full economic cycle.
Safety: the FSCS and who stands behind this account
Bank of Scotland is authorised by the Prudential Regulation Authority and regulated by both the PRA and the Financial Conduct Authority, under registration number 169628. Eligible deposits held in the Business Bank Account are protected under the Financial Services Compensation Scheme (FSCS) up to £120,000 per eligible depositor, via the Lloyds Bank plc banking licence. For most small businesses, that means the full working balance is covered. The FSCS limit applies per banking licence though, and because Bank of Scotland, Lloyds Bank, and Halifax all sit under that same licence, businesses that also hold personal savings with those brands should know their combined eligible deposits share a single £120,000 limit across the group. The parent Lloyds Banking Group is a systemically important UK bank, subject to enhanced capital and liquidity requirements set by the Bank of England. That institutional weight's a meaningful backstop beyond the FSCS, and it's one of the credible reasons why businesses in regulated sectors or with significant cash reserves still choose an established UK clearing bank over a newer authorised institution.
Verdict: open it if this matches you, look elsewhere if it does not
Bank of Scotland Business Bank Account earns its place as a reliable, conventional choice.
It suits UK businesses that want branch access, an established brand, and a free first year to ease the early trading period, provided this is genuinely the business's first current account with the bank. The current opening offer, a £200 boost plus six months of Xero free and a £200 Amazon gift card, makes the economics of starting out genuinely attractive while it lasts. The account's card now works with Apple Pay and Google Pay too, closing a gap that used to be a real reason to look elsewhere. If your business trades predominantly in sterling, holds modest cash balances, and values telephone and in-person support alongside a capable app, it delivers those things competently.
The honest case against it is shorter but sharper. Post-year-one, £10 a month buys a feature set that several free or near-free alternatives now match on core functionality, and there still aren't any virtual cards or bulk CSV payment uploads for businesses that pay several suppliers at once. Any business with meaningful international spend will pay a premium through the non-sterling card fee and the international and correspondent-bank fee schedule, one that compounds year on year. The Trustpilot score, while not business-specific, is a genuine warning sign about how slow a call to customer service can be if something goes wrong, even though the app itself is well reviewed.
Open this account if you're a new UK business in its first year of trading with Bank of Scotland, prefer a bank with branches, and expect most of your volume to stay in sterling. Look elsewhere if you need virtual cards, bulk payment uploads, or regularly move money in other currencies, where the fee schedule adds up faster than it first appears.
How safe is Bank of Scotland Business Bank Account?
Bank of Scotland Business Bank Account vs alternatives
A direct comparison of the key conditions against the strongest competitors in the market.
 |  |  |  | |
| Rating | 3.5 /5 | 5.0 /5 | 4.2 /5 | 4.2 /5 |
| Monthly fee | Free for 12 months, then £10/month | £0.00 | £0 (£25 if avg. balance below £10,000) | Free |
| Debit card | ✓ | ✓ | ✓ | ✓ |
| Credit card | ✓ | ✗ | ✗ | ✗ |
| Virtual credit cards | ✗ | ✗ | ✓ | ✓ |
| Free cash withdrawal | ✗ | ✓ | ✓ | ✗ |
| Number of sub-accounts | plan dependent | – | Several | Several |
| Online banking users | Several | – | Several | Several |
| Electronic transfers | ✓ | ✓ | ✓ | ✓ |
| Apple Pay | ✗ | ✓ | ✓ | ✗ |
| Google Pay | ✗ | ✓ | ✓ | ✗ |
| 3D Secure for online payments | ✓ | ✓ | ✓ | ✓ |
| Deposit protection | £120,000 | £120,000 | £120,000 | Nein (safeguarded, not FSCS) |
How we rate
About the author