
Monzo Savings Pots: review 2026
Last updated: 09.10.2026
Contents
Summary
Monzo Savings Pots let you earn interest on ring-fenced cash without leaving the Monzo app, making them a genuinely convenient option for existing Monzo customers. The free instant-access rate of 2.75% AER is decent but trails the best specialist easy-access accounts, while paid plans lift that to 3.00% (Extra), 3.25% (Perks) or 3.50% AER (Max), and a Fixed Rate Pot pays up to 4.70% AER if you lock funds away. This product suits savers who already bank with Monzo and want simplicity over the absolute highest rate.
Pros
- Instant-access savings managed entirely inside the Monzo app
- FSCS protection up to 120,000 GBP per person
- Interest credited regularly without locking funds away
- Automated saving tools such as round-ups and salary sorter
- Fixed Rate pots pay up to 4.70% AER for committed savers
Cons
- Instant-access rate of around 2.75% AER trails the top specialist easy-access accounts
- Best rates on fixed pots require funds to be locked away for the full term
- Rates are variable and Monzo can change them without notice
Key facts
| Interest on savings account | Free 2.75% AER; Extra 3.00% AER; Perks 3.25% AER; Max 3.50% AER (all variable instant access); Fixed Rate Pot up to 4.70% AER |
| Deposit protection | £120,000 |
| Online account opening | ✓ |
| Welcome bonus | – |
| Joint account | – |
| Overdraft interest rate | – |
| Savings account | – |
| Rating | 4.0 /5 |
Interest rate comparison
The effective annual rate compared directly with the alternatives.
A closer look
What Monzo Savings Pots are and who they suit
Monzo Savings Pots sit inside your existing Monzo current account as ringfenced pots of money that earn interest. You don't open a separate savings account with a different institution, log into a new portal, or wait days for a transfer to clear. The money moves in seconds, and the interest appears inside the same app you're already using for everyday spending.
For anyone who already banks with Monzo, that convenience is genuinely hard to beat.
The product works best for people who want accessible, automated savings and don't mind a rate that sits slightly below the very best specialist easy-access accounts. Salaried workers, freelancers, and younger adults who'd rather keep things simple than squeeze out every last basis point will find it a natural fit, and in our test, setting up a pot took under two minutes while the round-up rules and recurring deposit features worked exactly as advertised. Savers chasing the single highest instant-access rate should look elsewhere: dedicated savings apps such as Chip or a cash ISA through a building society will typically edge ahead. Monzo Savings Pots aren't the right vehicle either if you need a named, standalone savings account for mortgage affordability checks, or if you want to hold more than the FSCS protection limit of £120,000 in one place. Customers on the free Monzo tier should also note that the best instant-access rates are reserved for Extra, Perks, or Max subscribers. Anyone thinking about switching will find options among the Chip alternatives.
Interest rates explained: what you actually earn and when
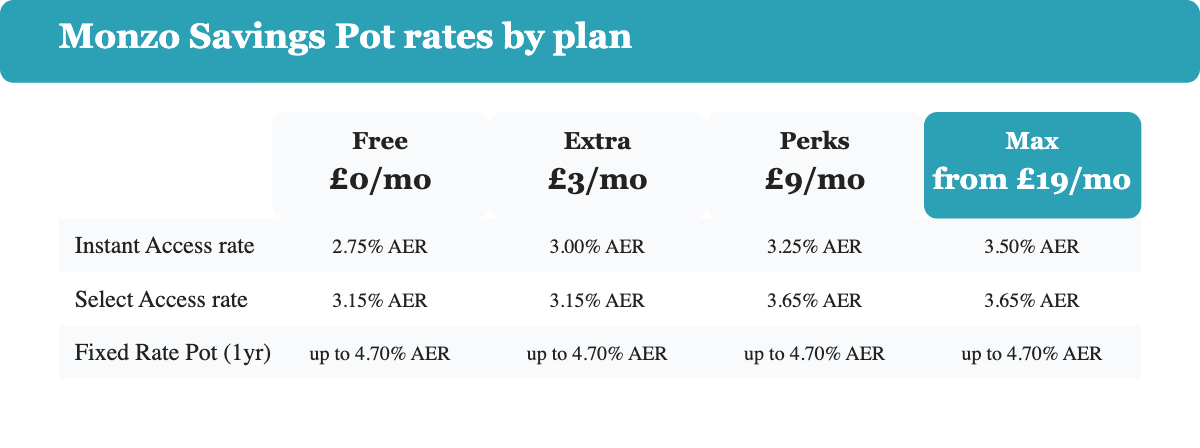
Monzo now runs four Instant Access Savings Pot rates, one per account plan. Free account holders earn 2.75% AER, the £3-a-month Extra plan lifts that to 3.00% AER, Perks (£9 a month) pays 3.25% AER, and Max (from £19 a month) pays the top instant-access rate of 3.50% AER, all variable.
AER stands for Annual Equivalent Rate. It's the standardised figure that lets you compare accounts on a like-for-like basis, regardless of how often interest is compounded or credited. We've collected the full price list in Monzo fees. Interest itself is calculated daily and credited to your pot monthly, so you don't have to wait until the end of a year to see it building up.
Two further pot types sit above instant access. The Select Access Savings Pot pays 3.15% AER on the free tier or 3.65% AER with Perks or Max, but it needs a £500 minimum deposit and allows no more than two withdrawals a year before the rate drops.
The Fixed Rate Savings Pot locks your money away entirely: 4.70% AER fixed for a 1-year term, or 4.60% AER fixed for 2 or 3 years, also from a £500 minimum, with no withdrawals permitted until maturity. If a fixed-term pot does allow an early exit in practice, the terms vary by case and should be read closely before you commit. It doesn't have to be this provider, either; we lined up the best Monzo alternatives if you'd rather compare first.
You may also see Monzo advertised elsewhere at a headline 5.00% AER through the 2026 Saving Challenge, a gamified Pot open to Monzo plan holders (Extra, Perks, Max) aged 18 and over, not a general savings account. It starts at 1p on day one and adds a penny more each day, reaching a final daily top-up of £3.65 on day 365; added together, those daily deposits total £667.95 by the end of the year at the standard pace, or roughly double or quadruple that with the optional 2x or 4x multiplier. You can't add money to it outside the daily schedule, so it works as a fixed, structured saving habit rather than a flexible pot for a lump sum.
All of these rates are variable except the fixed-term pots, and Monzo can and does adjust the instant-access and Select Access rates in line with Bank of England base rate movements. If maximising rate matters to you, it's worth checking the current figure inside the app before you deposit a large sum, since published figures online can lag the live product. If you're still shopping around, start here: Monzo vs Chase.
- Free: 2.75% AER instant access
- Extra (£3/month): 3.00% AER instant access
- Perks (£9/month): 3.25% AER instant access, 3.65% AER on Select Access
- Max (from £19/month): 3.50% AER instant access, 3.65% AER on Select Access
- Fixed Rate Pot: 4.70% AER for 1 year, 4.60% AER for 2-3 years, funds locked for the full term
- Interest credited: monthly to your pot
UK taxation on savings interest: how it applies here
Interest earned in a Monzo Savings Pot is taxable income in the UK. It isn't held in an ISA wrapper, so it doesn't receive any ISA tax shield. Instead, it falls under the Personal Savings Allowance introduced in 2016, which gives basic-rate taxpayers a £1,000 annual allowance of tax-free savings interest and higher-rate taxpayers a £500 allowance. Additional-rate taxpayers don't get any allowance at all.
In practice, across the 2.75% to 3.50% instant-access range, a basic-rate taxpayer would need to hold roughly £28,500 to £36,000 in Savings Pots before the £1,000 allowance runs out, and less again on the higher fixed or Select Access rates. For most people saving modest sums, no tax will be owed.
Savers who already earn significant interest elsewhere, across ISAs, Premium Bonds, or other savings accounts, need to look at the combined total, not just this one pot. HMRC receives interest data directly from financial institutions, so you don't need to file a self-assessment return purely because of Savings Pot interest unless your total taxable income exceeds the self-assessment threshold or you're already in self-assessment for another reason. If you're unsure, HMRC's online tools or a conversation with an accountant will clarify your position. Monzo also provides an annual interest statement in the app, which helps if you do need to file.
Opening a Savings Pot: step by step
You need an active Monzo current account before you can open a Savings Pot. If you're not yet a Monzo customer, the current account itself is opened entirely via the iOS or Android app using a video selfie and a photo of your passport or UK driving licence. Most applicants receive a decision within minutes and a physical card in the post within a few days.
UK residency and a UK mobile number are required. Monzo's standard personal current account is open from age 16, with a separate under-16s account for younger customers. Once your current account is active, opening a Savings Pot is three taps: go to the Home tab, tap Add a pot, then select Savings. You choose the pot type (Instant Access, Select Access, or Fixed Rate), name your pot, set an initial deposit, and confirm. Select Access and Fixed Rate pots need a £500 minimum deposit; Instant Access pots don't. You can hold up to 20 pots at once, each with its own name and image, which makes it easy to separate different savings goals without opening separate accounts.
Instant Access pots have no notice period, and withdrawals land back in your Monzo main account within seconds during normal operating hours. Select Access pots allow up to two withdrawals a year before losing the higher rate, and Fixed Rate pots permit none before maturity. Monzo's app supports both manual top-ups and automated rules, so you can round up every card purchase to the nearest pound, deposit a fixed amount on payday, or set a savings goal with a target date. In our test the round-up feature worked seamlessly across contactless and online transactions without any manual steps after initial setup.
Safety: FSCS protection today
Monzo Savings Pots are protected by the Financial Services Compensation Scheme (FSCS) up to £120,000 per eligible person. That limit rose from £85,000 on 1 December 2025 and is confirmed in Monzo's own FSCS Information Sheet. Joint holders are each covered separately, so a joint arrangement carries up to £240,000 of protection in total.
The FSCS is the UK's statutory deposit protection scheme, established under the Financial Services and Markets Act 2000. It's funded by a levy on FSCS-authorised firms and backed by the UK government as a last resort. Monzo's current FSCS Information Sheet no longer names the third-party partner banks that earlier versions of this page referenced, though some third-party guides still describe a partner-bank structure for specific pot types, and they disagree with each other on which banks are involved. Rather than repeat an unverified list, the safer approach is to check the app: Monzo discloses which institution actually holds a given pot at the point you open it, and the FSCS limit applies to whichever institution that is, separately from your main Monzo current account balance if it turns out to be a different one.
Monzo Bank Limited itself is FCA-authorised and PRA-regulated: the Prudential Regulation Authority (PRA) covers prudential matters and the Financial Conduct Authority (FCA) covers conduct matters. Monzo has held a full UK banking licence since 2017, and while its annual accounts show managed losses as it scales, revenue has grown consistently rather than shrunk.
Reputation and real customer experience
Monzo consistently scores among the highest of any UK bank in the Competition and Markets Authority's bi-annual service quality survey, particularly for mobile app quality and likelihood to recommend. Monzo also won Finder's 2025 Provider of the Year award for current accounts, packaged accounts, and joint accounts. On Trustpilot and in the Apple App Store, the recurring themes among positive reviews are the clarity of the interface, instant notifications, and the ease of saving without thinking about it. Customers who use the automated round-up and scheduled pot rules frequently describe saving meaningfully more than they did with a traditional bank's savings account, not because the rate is higher but because the friction is lower.
Recurring complaints tend to cluster around customer service response times during periods of high demand, occasional delays in resolving disputed transactions, and account freezes triggered by fraud-detection systems that can feel disproportionate.
A minority of reviews mention frustration that the instant-access rate lags behind specialist savings platforms, a point independent comparison sites echo: Monzo's best easy-access rate trails the market's best by more than two percentage points. These are fair criticisms, though the fraud-freeze issue isn't unique to Monzo; it's common across digital-first banks that apply aggressive transaction monitoring.
Among savings-specific feedback, customers generally appreciate that pot interest is clearly displayed alongside balance in the app, so it's easy to see what they've earned month by month. The main practical complaint about Savings Pots specifically is that the four-tier plan structure (Free, Extra, Perks, Max) makes comparing the actual rate uplift against the subscription cost harder than it needs to be, especially since the headline rate difference between tiers is often under a percentage point.
Verdict: open a Savings Pot, or look elsewhere?
Monzo Savings Pots deserve their place as a serious option for UK savers, but the right audience is specific. If you already use Monzo as your main current account and want a frictionless way to separate and grow your savings without managing a second institution, the product is close to ideal.
The app integration, automation features, and FSCS protection up to £120,000 make it a safe and genuinely convenient choice. Upgrading to a paid plan to unlock a higher rate only makes financial sense once the extra interest earned clears the monthly subscription fee, though; for most balances under five figures, that crossover point favours staying on Free or Extra rather than jumping straight to Max.
The case for looking elsewhere is just as clear. Rate-focused savers with a separate savings relationship at a building society or through a cash ISA will often find better returns without the subscription overhead, and the market's best easy-access and fixed-rate deals currently run well above Monzo's own. If you want the full £120,000 FSCS protection ring-fenced cleanly in a single named account, a standalone easy-access account from a specialist provider removes any ambiguity about which institution holds your money. And if you're not already a Monzo customer, the value proposition depends heavily on whether you want to switch your main banking relationship, not just add a savings pot.
For the right customer, convenience and integration tip the balance firmly in Monzo's favour. For rate maximisers and those who prefer a clean institutional boundary around their savings, the alternatives are worth a look before committing.
How safe is Monzo Savings Pots?
Monzo Savings Pots vs alternatives
A direct comparison of the key conditions against the strongest competitors in the market.
 |  |  |  | |
| Rating | 4.0 /5 | 4.0 /5 | 4.0 /5 | 4.0 /5 |
| Interest on savings account | Free 2.75% AER; Extra 3.00% AER; Perks 3.25% AER; Max 3.50% AER (all variable instant access); Fixed Rate Pot up to 4.70% AER | 2.25% AER variable (Boost: 4.50% AER for 12 months for new customers, requires a Chase current account) | ca. 3.50% AER easy access (Promo Boost: up to 5.01% AER for 6 months for new customers) | ca. 3.75% AER easy access (incl. 0.49% bonus for 12 months) |
| Deposit protection | £120,000 | £120,000 | £120,000 | £120,000 |
| Online account opening | ✓ | ✓ | ✓ | ✓ |
| Welcome bonus | – | ✓ | – | – |
| Joint account | – | ✗ | – | ✓ |
| Overdraft interest rate | – | ✗ | – | – |
| Savings account | – | ✓ | – | – |
How we rate
About the author
Frequently asked questions
Anyone with an active Monzo personal current account can open an Instant Access Savings Pot, which has no separate minimum age of its own beyond Monzo's standard current account age of 16. Select Access and Fixed Rate pots additionally require a £500 minimum deposit.
There are no fees to open or maintain a Savings Pot on the free Monzo account. Monzo Extra (£3 a month), Perks (£9 a month), and Max (from £19 a month) are paid plans that unlock higher instant-access and Select Access rates, so those plans carry a monthly subscription cost.
Savings Pots are covered by the FSCS up to £120,000 per eligible person, the limit that applies to Monzo Bank Limited since the FSCS raised its deposit protection ceiling from £85,000 on 1 December 2025. Monzo now holds Savings Pot funds directly rather than through the third-party partner banks it used in earlier years, so this limit covers your pots and your current account balance together.
Download the Monzo app, open a current account if you don't have one already (identity verification takes a few minutes), then tap 'Add a pot' on the home screen. Choose Instant Access, Select Access, or Fixed Rate, set your deposit, and confirm. The whole process takes under five minutes for existing account holders.
Yes, Monzo Bank Limited is authorised by the Prudential Regulation Authority and regulated by the FCA and PRA in the United Kingdom. Deposits receive FSCS protection up to £120,000 per person, and the app uses biometric login, real-time fraud alerts, and instant card controls.
Most UK taxpayers won't owe tax on Savings Pot interest because of the Personal Savings Allowance: up to £1,000 a year is tax-free for basic-rate taxpayers and up to £500 for higher-rate taxpayers. Monzo reports interest to HMRC directly, so eligible PAYE earners don't need to declare it separately.
Instant Access pots let you withdraw at any time and pay 2.75% to 3.50% AER depending on your plan. Select Access pots pay a higher 3.15% to 3.65% AER but cap you at two withdrawals a year and need a £500 minimum, while Fixed Rate pots pay the highest rate, 4.60% to 4.70% AER, in exchange for locking your money away for 1 to 3 years.