
NS&I Direct Saver: review 2026
Last updated: 05.11.2026
Contents
Summary
The NS&I Direct Saver is a straightforward easy-access savings account backed 100% by HM Treasury, making it unlike any other savings product on the UK market. It pays 3.75% AER gross on balances from just £1, can be opened jointly, and needs no notice period for withdrawals. It suits cautious savers who prioritise absolute security over chasing the very highest rate.
Pros
- 100% HM Treasury guarantee with no upper limit on deposit protection
- no monthly fees and no minimum deposit beyond £1
- instant access with no notice period or withdrawal penalty
- interest paid gross at 3.75% AER without tax deducted at source
- can be opened as a joint account
- straightforward online and phone account management with no hidden conditions
Cons
- 3.75% AER can still trail the best easy-access rates from challenger banks and building societies in 2026
- no dedicated mobile app, only online banking and telephone
- variable rate can be cut at any time with limited advance notice
- £2 million maximum holding per person may constrain very high-net-worth savers
Key facts
| Interest on savings account | 3.75% AER / 3.75% gross variable |
| Deposit protection | 100% HM Treasury guarantee (unlimited) |
| Online account opening | ✓ |
| Welcome bonus | ✗ |
| Joint account | ✓ |
| Overdraft interest rate | ✗ |
| Savings account | ✓ |
| Rating | 3.8 /5 |
Interest rate comparison
The effective annual rate compared directly with the alternatives.
A closer look
Overview: what the NS&I Direct Saver is, and who should skip it
The NS&I Direct Saver is a variable-rate easy-access savings account backed entirely by HM Treasury. It sits outside the Financial Services Compensation Scheme (FSCS) framework that covers most UK bank deposits, because NS&I itself is a government agency. Your money is not merely protected up to a limit; it is a direct obligation of the UK government with no ceiling. That is a genuinely unusual proposition in the British savings market. NS&I itself describes the arrangement as 100% security on deposits, and it serves more than 24 million customers with over £240 billion invested across its products. It is a different product from the NS&I Direct ISA, Income Bonds and Premium Bonds, which sit alongside it on NS&I's own products page but carry different rates, tax treatment and access rules.
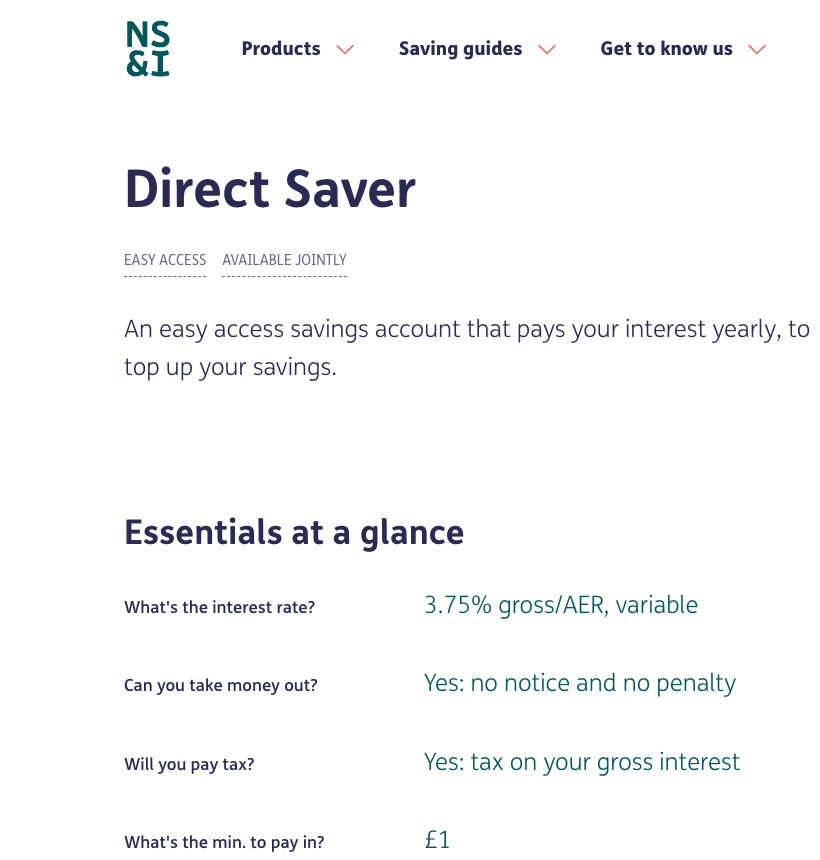
As of 5 November 2026, the account pays 3.75% gross/AER variable, requires a minimum opening deposit of just £1, and imposes no notice period before withdrawals. There are no fixed terms, no penalties, and no lock-in. Interest is paid gross, meaning NS&I doesn't deduct tax at source. You declare and pay any tax liability yourself via self-assessment or through your PAYE code adjustment, as applies to most UK savings income. This comparison shows where the offer sits: Best joint savings account.
The account suits cautious savers who prioritise absolute security over chasing the highest rate on the market, people with balances well above the £120,000 FSCS limit who cannot spread funds across multiple banks easily, and anyone who finds the idea of a government-backed institution psychologically reassuring. The FSCS limit rose from £85,000 to £120,000 on 1 December 2025, and even that increased limit still carries a cap that the Direct Saver does not have; the FSCS separately protects qualifying temporary high balances, such as proceeds from a house sale, up to £1.4 million for only six months. In our test it was also a practical choice for those who want simple, no-frills access without the need for a smartphone app. More providers are listed here: Best business savings account.
It is emphatically not the right home for money if rate maximisation is the primary goal. Challenger banks and building societies routinely offer easy-access rates above NS&I's 3.75%, sometimes by a meaningful margin. Nor is it suitable for savers who want to manage everything from a mobile app, since NS&I offers only online and telephone access. The Direct Saver can be opened as a joint account, which is one point in its favour over some easy-access rivals.
The NS&I Direct Saver interest rate explained: how it works and what could change it
As of 5 November 2026, the rate is 3.75% gross/AER, variable. AER (Annual Equivalent Rate) standardises the rate assuming interest is compounded over a full year, giving a like-for-like comparison with other savings products. Because the Direct Saver pays interest annually, the gross rate and the AER are identical here. This is a variable rate, so the figure above is a snapshot, not a permanent fact. NS&I cut the rate to 3.05% gross/AER on 12 February 2026, down from 3.30% at the time, and then raised it again to 3.75% on 18 August 2026, a move independent rate trackers put at the third change in 12 months.
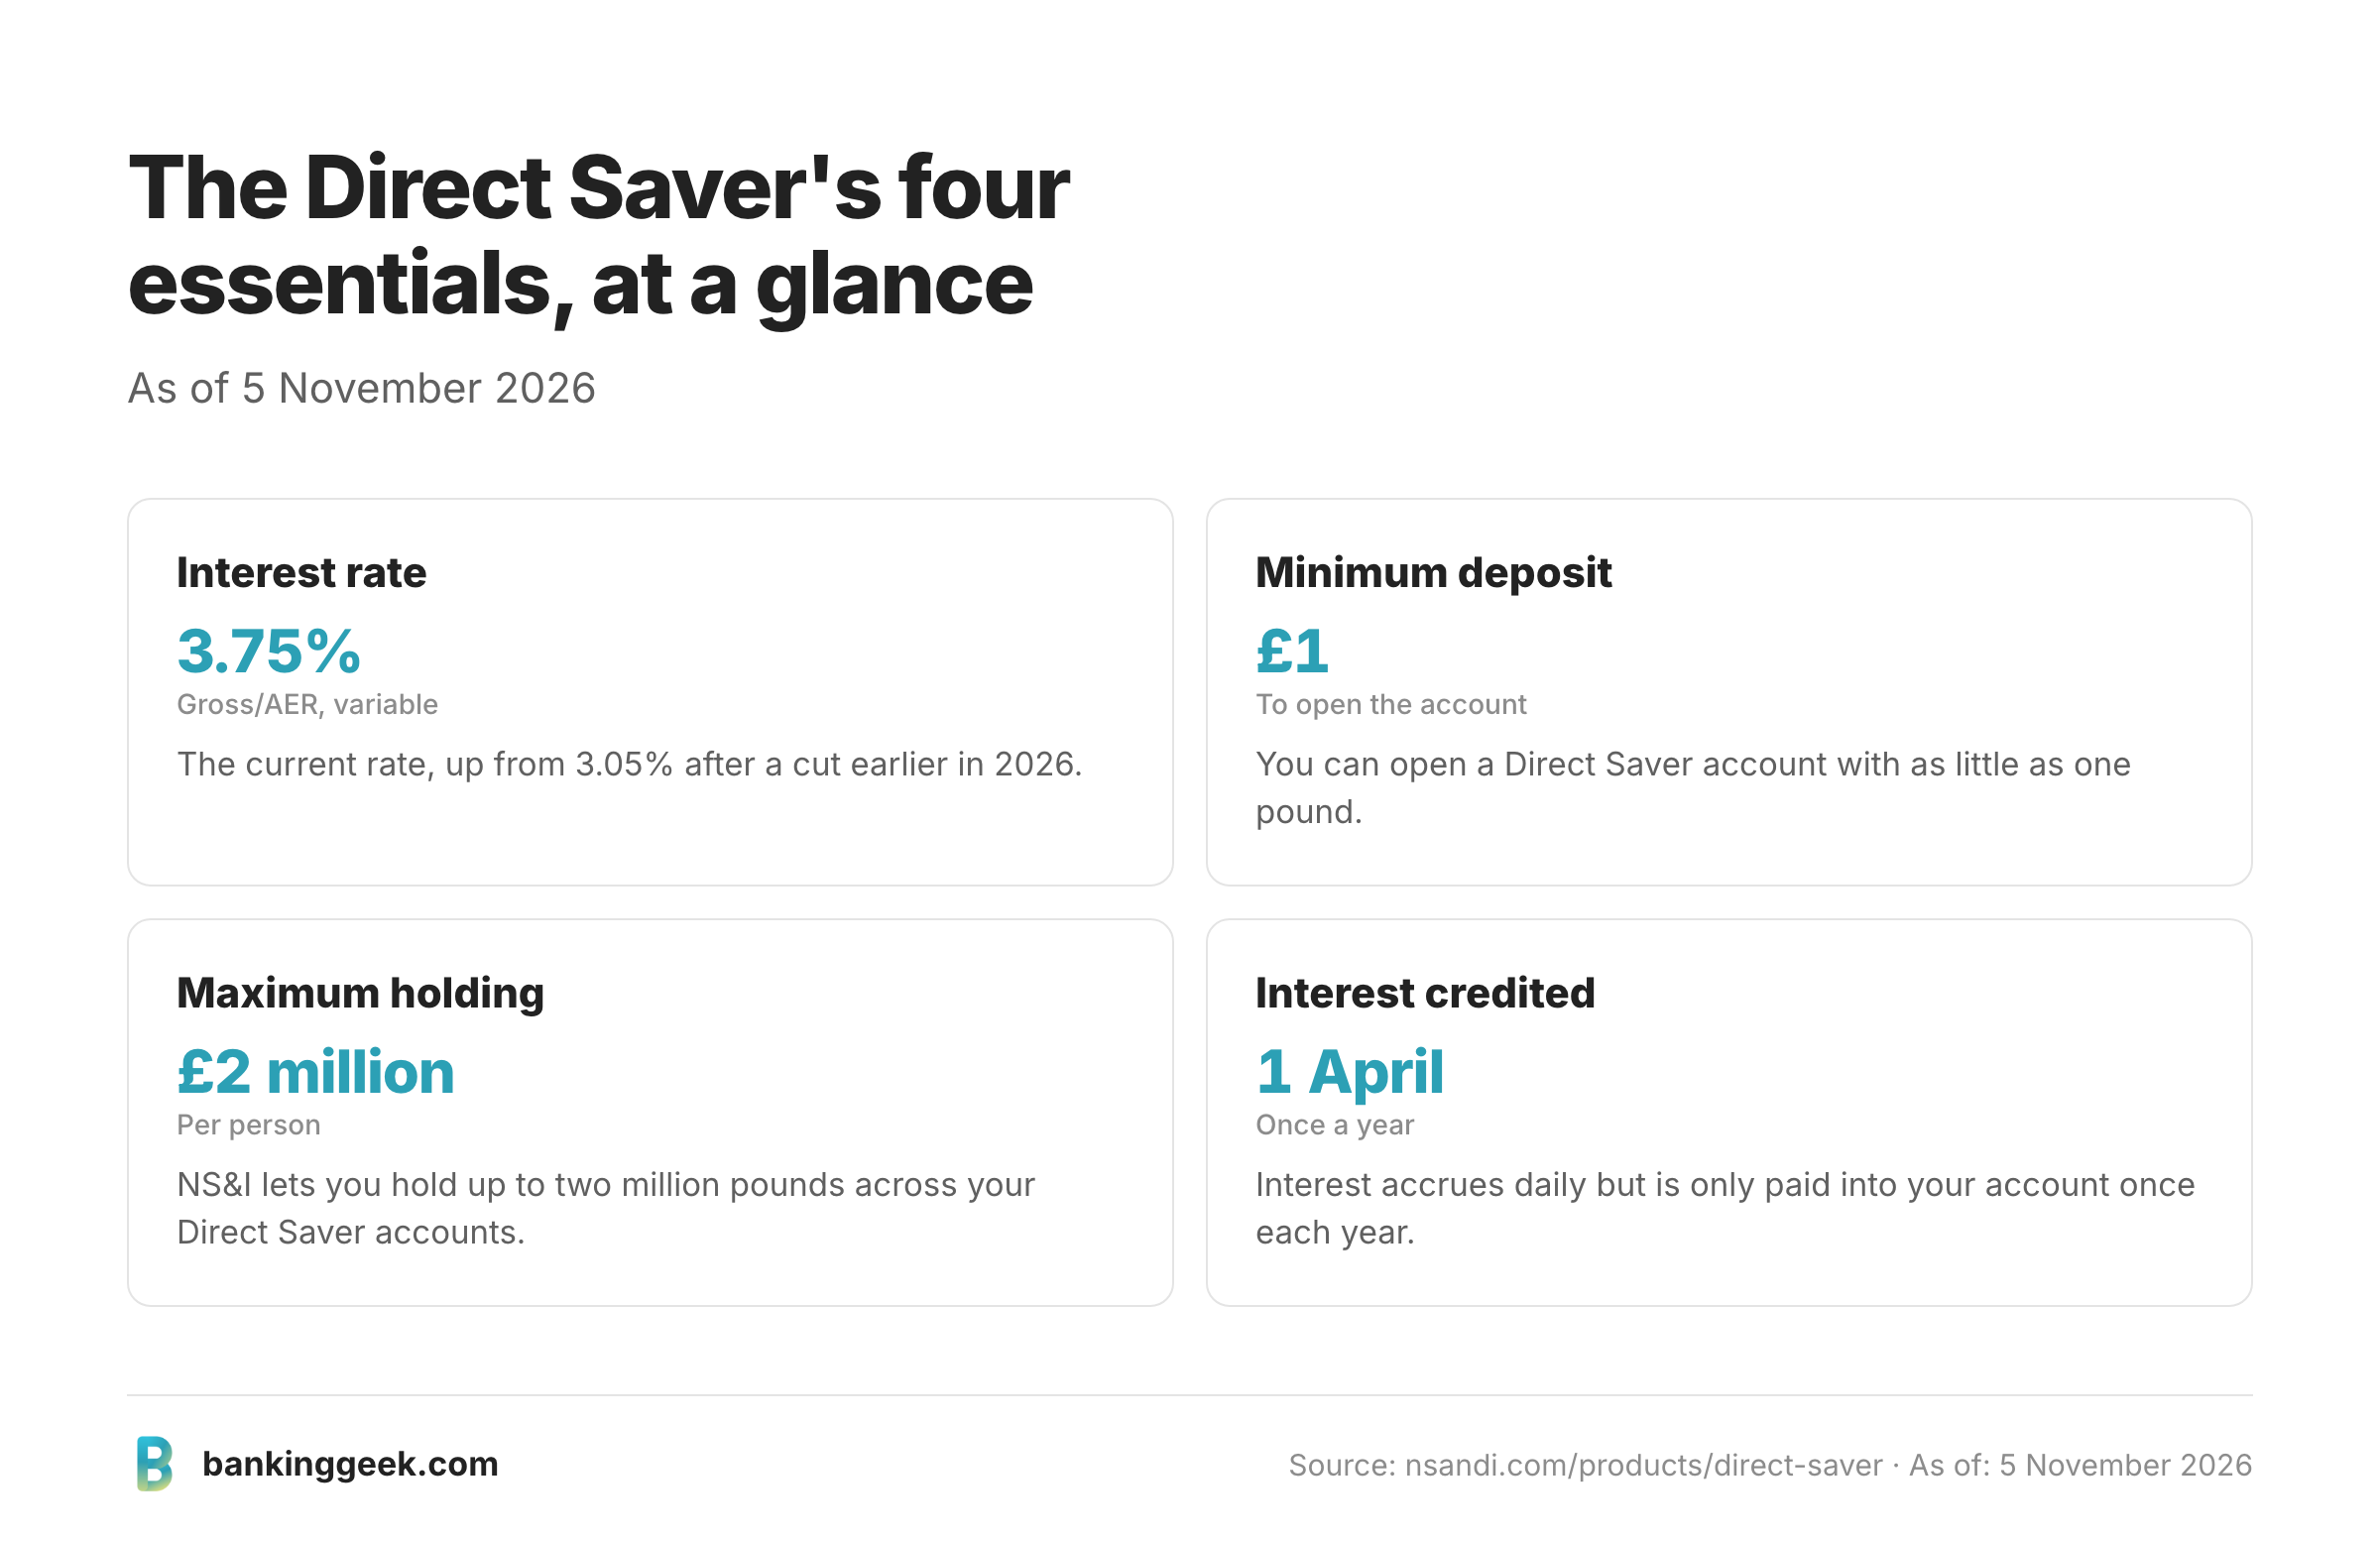
Interest accrues daily on the cleared balance, but it is credited to the account only once a year, on 1 April, rather than on the anniversary of when you opened the account. If you withdraw funds before that date, you still keep the interest already accrued for the days the money was held; NS&I doesn't forfeit accrued interest on withdrawals, which is an important distinction from some fixed-term accounts.
The rate is variable. NS&I can change it at any time, and historically has done so in response to Bank of England base rate movements and shifts in the wider savings market. There is no promotional or introductory bonus layered on top, no tiered structure where larger balances earn more, and no monthly-fee waiver linked to a minimum deposit. What you see is what you get: one flat rate, applied uniformly from £1 up to a maximum holding of £2 million per person.
That £2 million figure is a holding cap, not an annual payment-in limit: NS&I lets you hold up to £2 million per person across your Direct Saver accounts at any time. Most savers will never approach it, but very high-net-worth individuals who want to park large sums in a single government-backed vehicle should factor it into their planning.
Tax on your savings interest in the UK: what you actually owe
Interest from the NS&I Direct Saver is paid gross, without any tax deducted at source. That doesn't mean it's tax-free. The UK taxes savings interest under income tax rules, with the Personal Savings Allowance (PSA) providing a zero-rate band before your marginal rate applies.
Basic-rate taxpayers (20%) have a PSA of £1,000 per tax year. Higher-rate taxpayers (40%) have a PSA of £500. Additional-rate taxpayers (45%) receive no PSA at all and pay 45% on every penny of savings interest. If the interest credited to your Direct Saver in a tax year exceeds your PSA, you owe tax on the excess at your marginal rate.
HMRC typically collects this by adjusting your PAYE tax code the following year, reducing your tax-free pay to recover the amount owed. If you complete a self-assessment return, you declare the interest there instead. NS&I reports interest paid to HMRC automatically, so the figure should appear pre-populated in your self-assessment return. In our test of the account-management portal, the annual interest statement was clearly labelled and easily downloadable for tax purposes.
One point worth emphasising: because interest is credited annually rather than monthly, a basic-rate taxpayer earning 3.75% on a balance of around £26,650 would receive close to £1,000 in interest, using up the full PSA in a single account. Any balance above that threshold generates a tax liability, though the exact figure moves whenever the rate does. Planning around PSA limits across multiple accounts is therefore worthwhile.
Opening the account: step by step
The application is completed entirely online at nsandi.com. NS&I doesn't operate a mobile app for new account opening; you need a desktop or mobile browser. The process typically takes under fifteen minutes for an applicant who already holds a UK bank account, and NS&I aims to have the account open within 7 to 10 working days once identity checks clear.
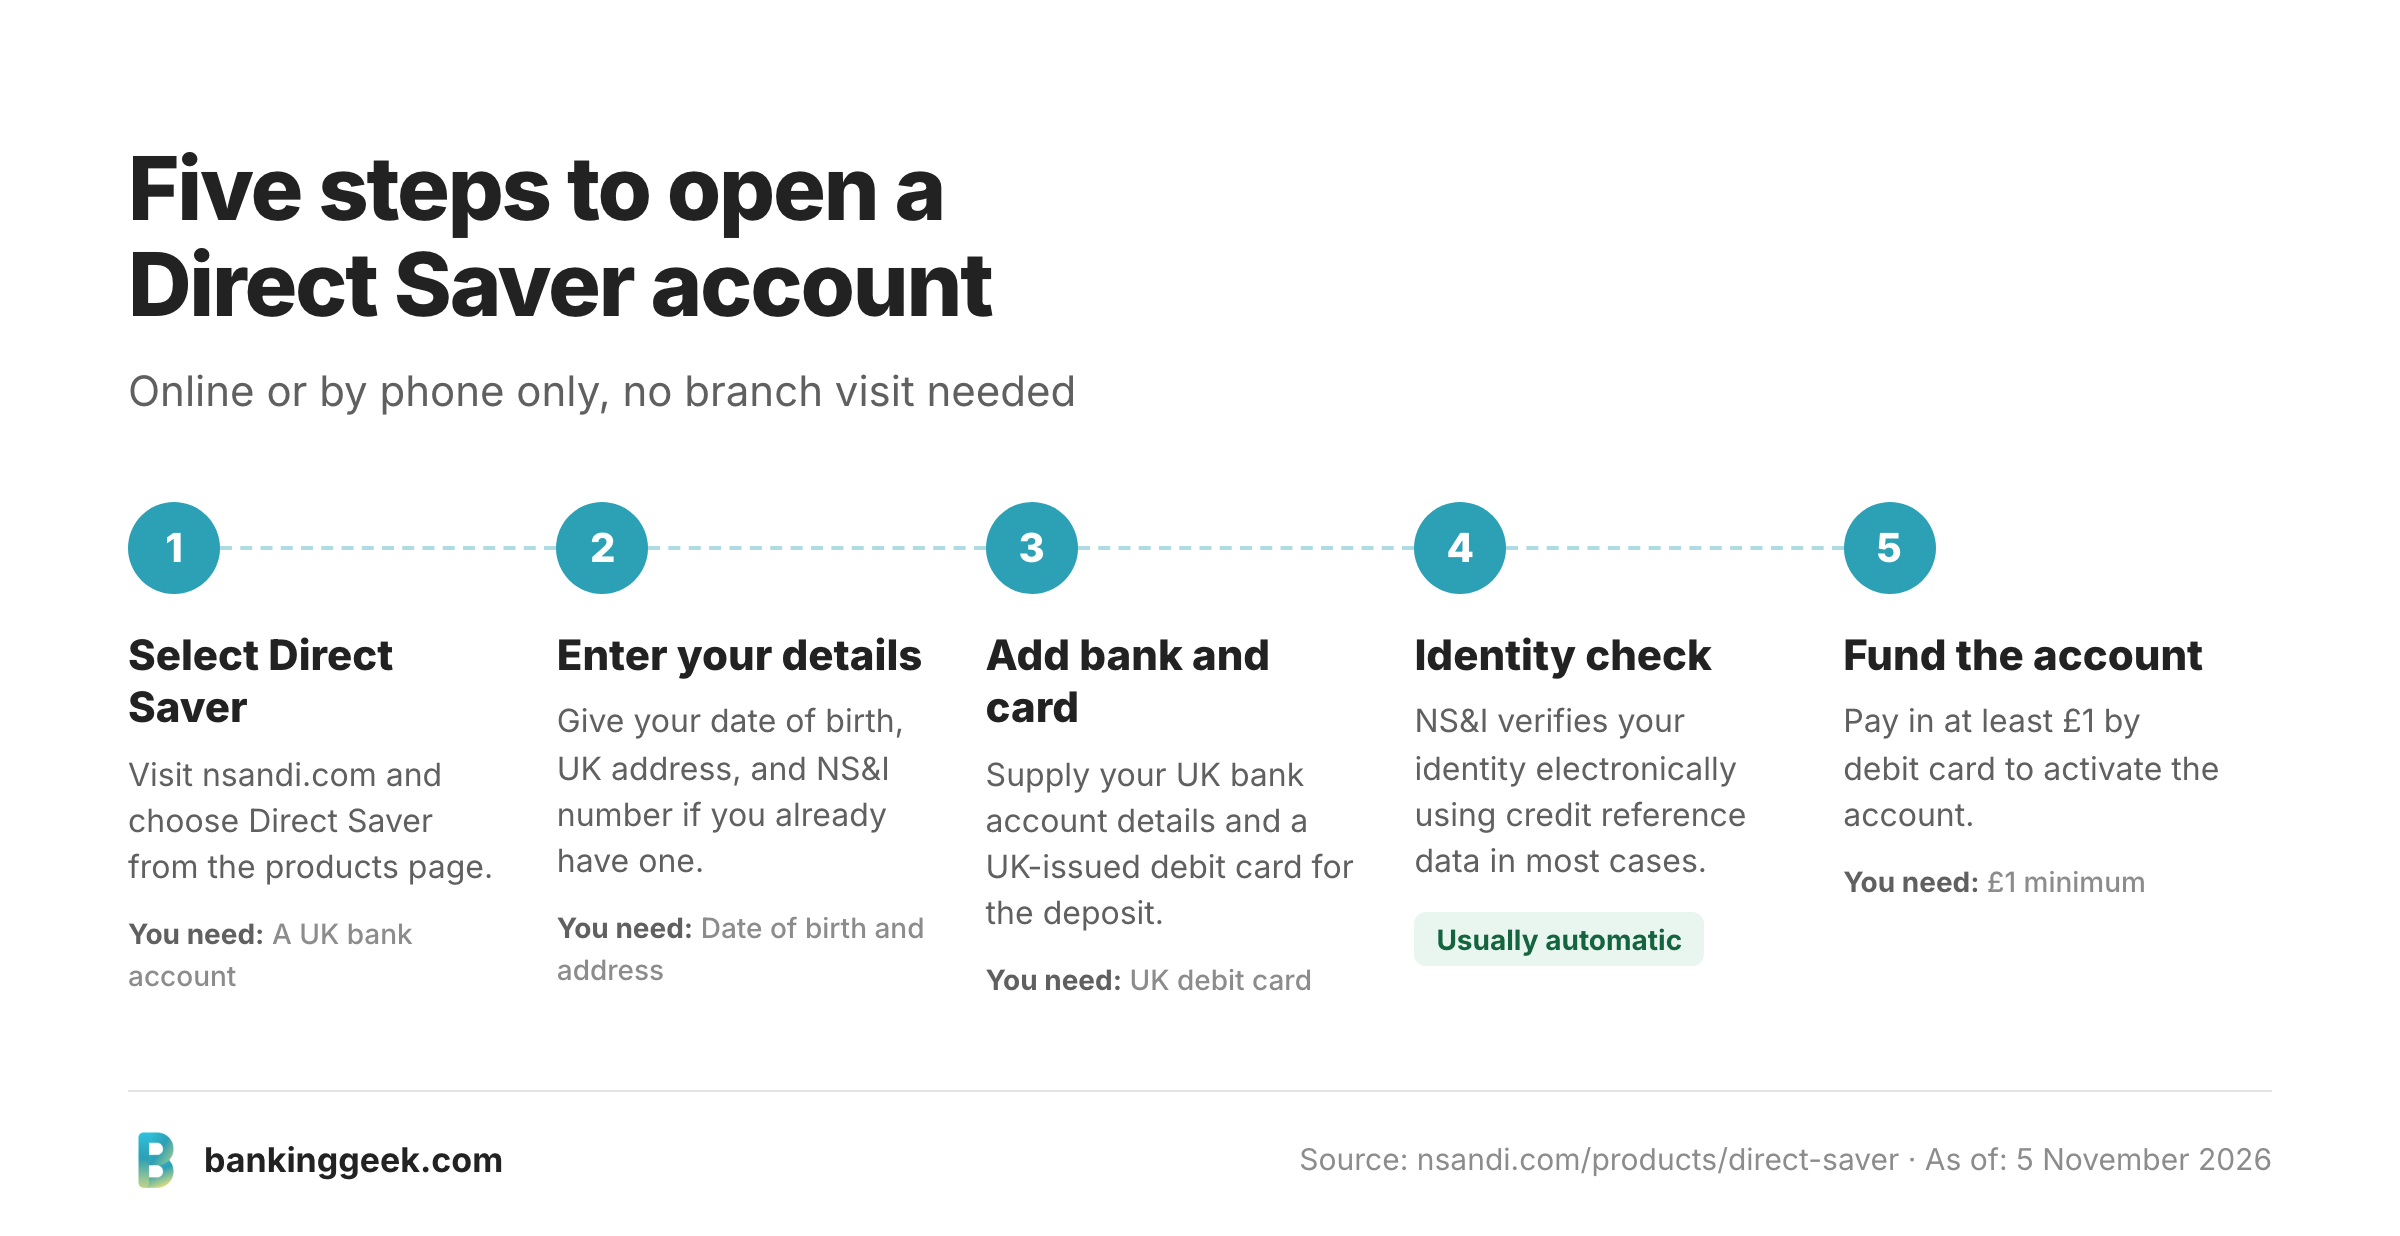
- Visit nsandi.com and select Direct Saver from the products page.
- Provide your NS&I number if you already have one, your date of birth, and your current UK address.
- Supply your UK bank account details and a UK-issued debit card. NS&I links withdrawals to a nominated bank account only, which adds a layer of security.
- NS&I verifies your identity electronically using credit reference agency data in most cases. No document upload is required for the majority of applicants.
- Make your opening deposit of at least £1 using your UK debit card. The account is activated once the funds clear.
Your NS&I customer number and account number arrive by post within a few working days. You also receive a password by post, kept separate from the customer number for security reasons. This old-fashioned two-letter approach is deliberate; NS&I manages accounts for millions of savers and maintains postal communication as a fallback. UK residents only can apply; NS&I doesn't accept non-UK residents. The IBAN format for NS&I accounts uses the standard GB prefix, though transfers are processed domestically via Faster Payments and BACS rather than international wire. There is no notice period for withdrawals and no penalty; you can request your money back at any time, with funds typically taking 3 to 5 working days to reach your nominated bank account.
App, online access, and customer service
NS&I doesn't offer a dedicated mobile app for the Direct Saver. Account management is via the online portal at nsandi.com, which is optimised for mobile browsers but is not a native app. You can check your balance, view transaction history, make deposits, request withdrawals to your nominated account, and download statements. For most straightforward tasks the portal is adequate.
Where NS&I falls short relative to modern challenger banks is in the breadth of in-app features. There are no spending insights, no savings goals, no round-up tools, and no instant push notifications. If you want a savings account that integrates into a broader financial management ecosystem, NS&I isn't that product.
Customer service is available by telephone on 08085 007 007. NS&I's virtual assistant answers general queries around the clock, but if you need to speak to a person, the team is available 8am to 8pm Monday to Friday and 8am to 6pm on Saturday and Sunday, closed on bank holidays. Wait times can be substantial during peak periods, particularly around NS&I rate-change announcements. The online secure messaging function provides a written alternative for non-urgent queries. NS&I also maintains a postal address for those who prefer traditional correspondence, and all key documents, including your customer number and password, arrive by post regardless of how you applied. In our test, a straightforward balance enquiry via the online portal was resolved in under two minutes without needing to call.
Reputation and real customer experience
NS&I carries a distinctive reputation in the UK savings market. Its association with Premium Bonds, the government guarantee, and decades of mass-market advertising create a high baseline of trust, particularly among older savers. Trustpilot reviews for NS&I as a whole skew positively on the security and reliability of the institution, with recurring praise for the peace of mind that the government backing provides and for the gross interest payment, which savers appreciate not having to reclaim.
Recurring complaints cluster around two themes. First, the online portal and account management experience draw consistent criticism for feeling dated compared with fintech competitors. Password delivery by post, the absence of a native app, and the clunky process of changing a nominated bank account are frequently cited frustrations. Second, rate decisions attract negative sentiment: whenever the Bank of England base rate moves and NS&I is slow to pass on an increase, or when NS&I cuts ahead of competitors, that draws vocal criticism in personal finance communities.
It's worth contextualising the complaints. NS&I serves a very large and demographically broad customer base, many of whom aren't primarily looking for the highest rate or the slickest app. For that audience, the product performs its core function well. For savers who arrived via a rate comparison site and are primarily optimising yield, disappointment is more likely because NS&I has never competed at the very top of the easy-access rate tables over sustained periods. The variable-rate risk is real: the rate has already moved three times in the past 12 months, from 3.30% to 3.05% and back up to 3.75%, and it could fall again if the Bank of England resumes cutting.
Verdict: open it, or look elsewhere?
The NS&I Direct Saver earns its place in the UK savings landscape for a specific type of saver. If you hold, or plan to hold, substantially more than £120,000 in savings and can't easily spread funds across enough banks to stay within FSCS limits everywhere, the unlimited government guarantee is a concrete, meaningful advantage that no FSCS-covered account can match. The same logic applies to trustees, charity treasurers, or anyone holding money on behalf of others who needs unconditional security above all else.
Basic-rate taxpayers who value simplicity and gross payment of interest, and who are not actively rate-chasing, will find the Direct Saver a perfectly functional home for an emergency fund or medium-term savings pot. The £1 minimum, the instant access, the option to open jointly, and the absence of any fees make it frictionless to maintain alongside other savings products.
You should look elsewhere if rate maximisation matters. At 3.75% gross/AER as of 5 November 2026, the Direct Saver sits below the best easy-access accounts available from building societies and digital banks, sometimes by a meaningful margin, and that gap moves every time NS&I adjusts the rate. For balances comfortably within FSCS protection limits, a persistent rate gap compounds into a real opportunity cost over time. Similarly, if you want a mobile-first experience, savings goals, or integration with open banking tools, the NS&I Direct Saver will feel like a step backward. It is an excellent product for the use case it was designed for, and a mediocre one for anything else.
How safe is NS&I Direct Saver?
NS&I Direct Saver vs alternatives
A direct comparison of the key conditions against the strongest competitors in the market.
 |  |  |  | |
| Rating | 3.8 /5 | 4.5 /5 | 4.3 /5 | 4.2 /5 |
| Interest on savings account | 3.75% AER / 3.75% gross variable | 4.71% AER variable (incl. 1.11% bonus for 12 months; standard rate 3.60% AER) | 4.70% AER variable (incl. 1.25% bonus for 12 months; standard rate 3.45% AER) | ca. 3.85% AER variable (Easy Access Saver); up to 7.50% AER (Member Regular Saver, 12 months) |
| Deposit protection | 100% HM Treasury guarantee (unlimited) | £120,000 | £120,000 | £120,000 |
| Online account opening | ✓ | ✓ | ✓ | ✓ |
| Welcome bonus | ✗ | ✓ | ✗ | ✗ |
| Joint account | ✓ | ✗ | ✗ | ✓ |
| Overdraft interest rate | ✗ | ✗ | ✗ | ✗ |
| Savings account | ✓ | ✓ | ✓ | ✓ |
How we rate
About the author
Frequently asked questions
UK residents aged 16 or over can open the account. You'll need your address, date of birth, UK bank account details and a debit card from a UK bank or building society. Companies, trusts and charities are not eligible, but the account can be opened jointly with another person.
No. The NS&I Direct Saver has no monthly maintenance fee, no minimum balance requirement beyond the opening £1, and no withdrawal penalty. The only structural limit is a £2 million maximum holding per person.
Unlike standard bank accounts, the Direct Saver is not covered by the FSCS £120,000 limit. Instead, every deposit is backed 100% by HM Treasury with no upper cap, making it one of the most secure savings products available in the UK.
You apply online at nsandi.com using a debit card from a UK bank or building society to fund the opening deposit. NS&I verifies most applicants' identity electronically, and the process typically takes under fifteen minutes. There are no branches to visit and no paper forms needed to open the account.
No. The 3.75% AER gross rate is variable and NS&I can change it at any time; if the rate falls, NS&I contacts existing customers personally in advance. Because the rate is variable, it is worth monitoring periodically and comparing with alternative easy-access accounts.
NS&I pays interest gross without deducting tax at source. Any interest you earn counts toward your Personal Savings Allowance: £1,000 for basic-rate taxpayers, £500 for higher-rate, and nil for additional-rate. Interest above your allowance must be declared to HMRC via self-assessment.