
Coventry Building Society Easy Access Saver: review 2026
Last updated: 24.10.2026
3.5 /5 ★★★★☆Good
Rank 44 of 50 in our comparison
Contents
Summary
The Coventry Building Society Easy Access Saver is a straightforward, no-frills savings account that keeps things simple: no withdrawal penalties, a low minimum deposit of just £1, and full FSCS protection up to £120,000. In our test, the account opened quickly online and worked well, but only if you can accept a variable rate of 2.00% AER that sits well below the best-buy easy access rates available in the UK right now. It suits cautious savers who prioritise simplicity and brand trust over chasing the top rate.
Pros
- Fully instant access with no withdrawal restrictions or penalties
- minimum deposit of just £
- 1 makes it accessible from age 16
- maximum balance of £
- 1,000,000
- FSCS-protected up to £
- 120,000 per person per bank
- managed entirely online and via iOS and Android app
Cons
- Variable rate of 2.00% AER is well below the best-buy easy access rates on the UK market
- no welcome bonus for new savers
- rate can be cut at any time
- joint account application requires completing a postal form rather than a fully digital process
Key facts
| Interest on savings account | 2.00% AER variable |
| Deposit protection | £120,000 |
| Online account opening | ✓ |
| Welcome bonus | ✗ |
| Joint account | ✓ |
| Overdraft interest rate | ✗ |
| Savings account | ✓ |
| Rating | 3.5 /5 |
Interest rate comparison
The effective annual rate compared directly with the alternatives.
A closer look
What is the Coventry Building Society Easy Access Saver, and who is it really for?
Coventry Building Society's been around since 1884, making it one of the older mutual institutions in Britain. It doesn't have shareholders, which means profits go back to members rather than distributed to investors. That ethos shapes the Easy Access Saver: a no-frills, fully liquid savings account for people who just want a safe home for their cash without locking anything away.
The account suits savers who prioritise flexibility above all else. Withdrawals are unrestricted and carry no penalties, so your money can come out on any working day without the account losing its rate or status. The minimum opening deposit is just £1, and balances can run up to £1,000,000, so it's equally accessible to someone building a small emergency fund or a retired professional parking a property sale. How it stacks up against the rest of the market is shown here: Best business savings account.
Equally important is who this account does not suit. Rate-chasers won't be happy here: the current variable rate of 2.00% AER sits well below both the average easy access rate and the best easy access rates the wider UK market pays. Anyone willing to accept a short notice period or a one-year fixed term can earn substantially more. Businesses can't hold this account. Savers under 16 can't apply either. And couples wanting a joint account should know the digital application covers only single holders; joint accounts need a postal form, which adds days to the process.
The interest rate explained: what 2.00% AER actually means for your money

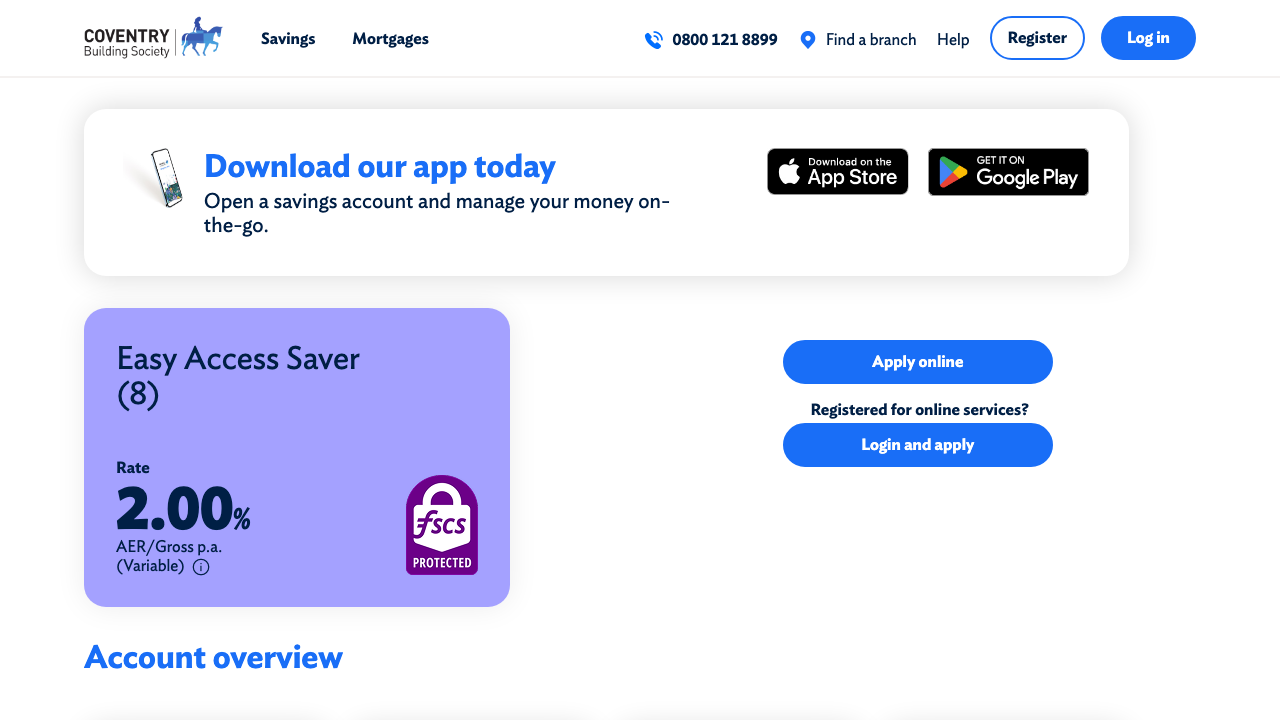
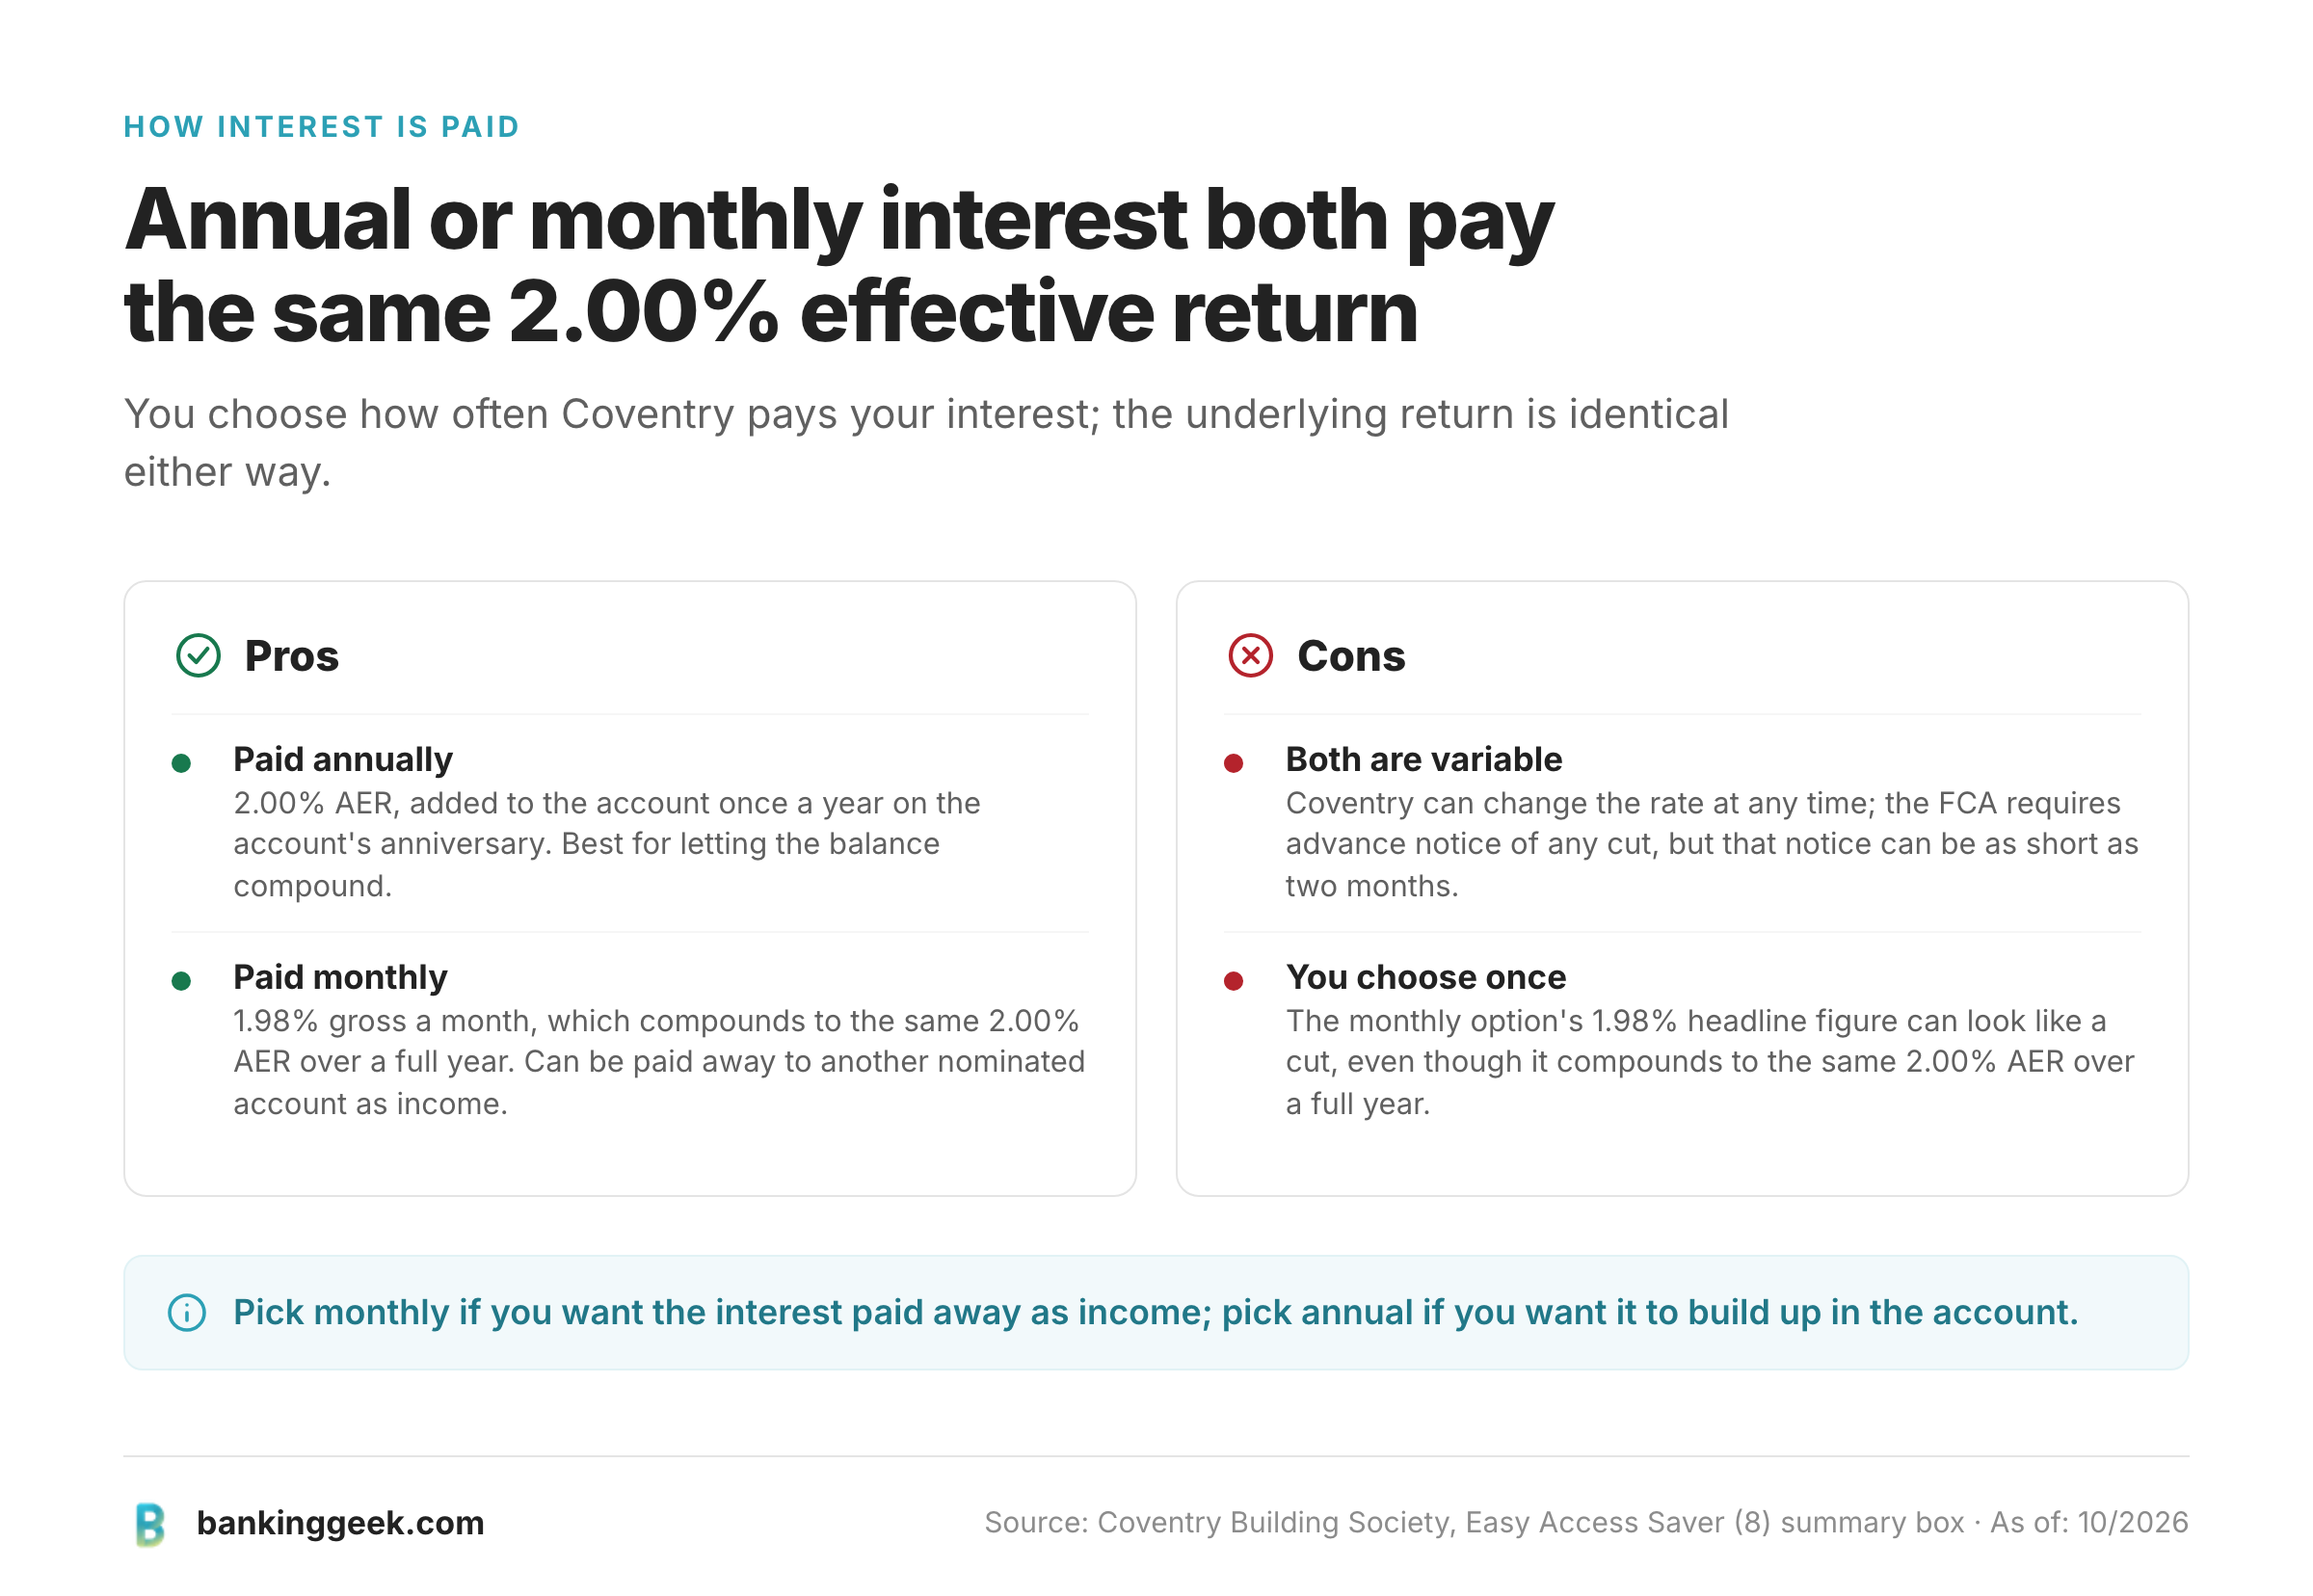
The headline rate is 2.00% AER variable. AER stands for Annual Equivalent Rate and is the standardised way UK savings products express their returns, accounting for how frequently interest compounds. Coventry lets you choose how interest reaches you: annually at 2.00% AER, or monthly at 1.98% gross, which compounds to the same return over a full year. Hold £10,000 for a full year on the annual option and you receive £200 before tax. There's no introductory bonus rate layered on top of a lower underlying rate; 2.00% is simply what the account pays from day one. If you're still shopping around, start here: Best children's savings account.
Variable means Coventry can move the rate up or down whenever it wants. Building societies are obligated under the Financial Conduct Authority's rules to give savers advance notice of any reduction, but that notice period can be as short as two months. At 2.00%, the account also pays less than UK CPI inflation, which stood at 3.50% in September 2026, so cash held here is losing purchasing power in real terms. In our test of the account opening and rate history, we found Coventry's been reasonably stable compared to some challenger banks that have shuffled rates aggressively, but the 2.00% figure's drifted downward relative to the wider market over the past 18 months.
There's no fee to hold the account, no monthly charge, and no minimum withdrawal. Interest accrues daily regardless of which payment frequency you pick. Savers who want a monthly income can set the account to pay interest away to a nominated current account at the end of each month; savers building a lump sum usually let it compound annually instead. Either way, you're earning the same underlying 2.00% AER.
Taxation of savings interest in the UK: the Personal Savings Allowance
UK residents benefit from the Personal Savings Allowance (PSA), introduced in 2016. Basic-rate taxpayers (20% band) can earn up to £1,000 of savings interest per tax year before paying any income tax. Higher-rate taxpayers (40% band) have a £500 allowance. Additional-rate taxpayers, those paying 45%, receive no allowance at all and must declare every pound of interest.
At 2.00% AER, a basic-rate taxpayer would need more than £50,000 in this account before they'd breach the £1,000 PSA threshold. Most savers who hold typical emergency fund balances won't owe anything. Above the allowance, interest is added to total income and taxed at the marginal rate via self-assessment or PAYE coding adjustment. Coventry reports the interest to HMRC automatically, so you don't need to make a separate declaration if you don't exceed the PSA.
Savers who want entirely tax-free growth should consider a Cash ISA instead, where interest never counts toward the PSA limit, no matter how much you've earned. The Coventry Easy Access Saver isn't an ISA, and it doesn't shelter interest from tax beyond the PSA.
Opening the account step by step
Applications for individual accounts are completed entirely online and typically take under fifteen minutes. The steps are:
- Visit the Coventry Building Society website and select the Easy Access Saver.
- Provide personal details: full name, date of birth, address history for the past three years, National Insurance number.
- Verify identity digitally via Coventry's integrated check (most applicants clear this automatically; a minority are asked to supply a document image).
- Fund the account with at least £1 by debit card or bank transfer from a nominated UK current account.
- Receive confirmation by email; the account is live immediately after funding.
There's no branch visit required, no paper form for single applicants, and no waiting period once the digital identity check passes. Withdrawals go back to the nominated current account and typically clear the same working day if you request them before the daily cut-off. The account doesn't have a notice period or a lock-in; your money's available on demand.
Joint accounts follow a different path. Both holders have to complete a postal application, which Coventry then processes manually. You'll want to expect at least five to seven working days from posting to activation. That's an unusual gap for 2026, and it may deter couples who expect a fully digital experience. For the wider picture, see our comparison: Best joint savings account.
Safety, the FSCS, and the building society model
Coventry Building Society is authorised by the Prudential Regulation Authority and regulated by both the PRA and the Financial Conduct Authority. As a UK-authorised deposit taker, it falls under the Financial Services Compensation Scheme (FSCS), which protects eligible deposits up to £120,000 per person per institution. The FSCS limit rose from £85,000 to £120,000 on 1 December 2025. Joint account holders each receive their own £120,000 protection, meaning a joint account holds up to £240,000 of FSCS coverage.
The maximum balance of £1,000,000 is technically permitted, but any amount above £120,000 held by a single person is unprotected in the event of the society failing. Savers with large sums to deposit should spread them across multiple FSCS-protected institutions rather than parking everything here. Coventry's operated continuously for over 140 years, holds strong capital ratios, and is the second-largest building society in the UK, which gives a reasonable degree of confidence in its stability, though past performance doesn't guarantee future safety.
As a mutual, Coventry doesn't answer to external shareholders. This structure historically correlates with more conservative balance-sheet management, though it doesn't change the regulatory protections available to depositors. The FSCS guarantee is the same whether the institution is a bank or a building society.
Reputation and real customer experience
Coventry Building Society consistently scores above the UK banking sector average on independent satisfaction surveys, including those published by the Competition and Markets Authority as part of its Retail Banking Market Investigation order. The recurring themes in positive reviews are reliability, clear communication about rate changes, and a customer service team reachable by telephone without excessive hold times.
In our test of the account, the application process was smooth, and identity verification passed in under two minutes. The online dashboard is functional rather than feature-rich; balance and interest accrued are clearly visible, as are transaction records. On Trustpilot, Coventry Building Society holds 4.4 out of 5 from more than 3,300 reviews, with the iOS and Android apps carrying broadly positive ratings in their own stores and users frequently praising the ability to move money quickly without needing to call.
Criticism follows predictable patterns. The rate is the most common complaint: reviewers note that competitors offer significantly higher returns without sacrificing access. A secondary frustration is the joint account process, which several users say feels outdated. Some customers say they struggle with the automated telephone menus when they call for support, though those who reach a human agent generally report good outcomes. There aren't widespread concerns about money being trapped, incorrect interest calculations, or unexplained account restrictions, which matters when you're assessing operational reliability.
Verdict: open it, or look elsewhere?
Open the Coventry Building Society Easy Access Saver if you need a dependable, fully liquid home for cash you want to keep accessible; look elsewhere if chasing the top rate matters more than convenience. The FSCS protection, the mutual ownership model, the genuinely unrestricted withdrawals, and the straightforward digital opening make it a sensible choice for an emergency fund or short-term cash holding where capital safety and instant access outweigh the pursuit of maximum yield.
Open it if you want a reputable UK building society account with no fees, no withdrawal penalties, and a simple online experience, and you won't be hit with surprise charges along the way. It's also a reasonable secondary account for spreading deposits across institutions to stay within FSCS limits.
Look elsewhere if yield is a priority. At 2.00% AER, this account trails both the average and the best easy access rates on the market by a meaningful margin. Savers comfortable with the same level of access can find notably higher rates from other FCA-regulated, FSCS-protected providers. Similarly, anyone wanting a joint account without postal paperwork, or tax-sheltered growth via a Cash ISA, should consider dedicated products designed for those needs; a monthly income payout, at least, is already built into this account. It's solid but unambitious, and the rate alone prevents a higher overall recommendation.
How safe is Coventry Building Society Easy Access Saver?
Coventry Building Society Easy Access Saver vs alternatives
A direct comparison of the key conditions against the strongest competitors in the market.
|  |  |  | |
| Rating | 3.5 /5 | 4.5 /5 | 4.3 /5 | 4.2 /5 |
| Interest on savings account | 2.00% AER variable | 4.71% AER variable (incl. 1.11% bonus for 12 months; standard rate 3.60% AER) | 4.70% AER variable (incl. 1.25% bonus for 12 months; standard rate 3.45% AER) | ca. 3.85% AER variable (Easy Access Saver); up to 7.50% AER (Member Regular Saver, 12 months) |
| Deposit protection | £120,000 | £120,000 | £120,000 | £120,000 |
| Online account opening | ✓ | ✓ | ✓ | ✓ |
| Welcome bonus | ✗ | ✓ | ✗ | ✗ |
| Joint account | ✓ | ✗ | ✗ | ✓ |
| Overdraft interest rate | ✗ | ✗ | ✗ | ✗ |
| Savings account | ✓ | ✓ | ✓ | ✓ |
How we rate
About the author
Frequently asked questions
The account is open to UK residents aged 16 and over. You need a UK address and, for online opening, a valid email address and mobile number for verification. Joint applications are possible but currently require a postal form rather than a fully digital process.
No. There are no monthly account fees and no penalties for withdrawals. You can take money out at any time without notice or cost. The minimum opening deposit is just £1 and the maximum balance allowed is £1,000,000.
The Easy Access Saver is covered by the FSCS, 120,000 GBP per person per bank. Coventry Building Society is a UK-authorised building society regulated by the FCA and PRA, so your deposits receive the same statutory protection as those held at a major high-street bank.
Individual applicants can open the account entirely online through the Coventry Building Society website or mobile app. The process typically takes under 15 minutes. Joint account applicants are required to complete and return a postal form, which adds several days.
Yes. The account is regulated by the FCA and PRA and your balance is protected up to £120,000 per person by the FSCS. Coventry Building Society has operated as a mutual building society for over 140 years and is one of the largest in the UK.
Interest earned counts towards your Personal Savings Allowance: £1,000 for basic-rate taxpayers and £500 for higher-rate taxpayers each tax year. Additional-rate taxpayers have no PSA and pay income tax on all interest. Coventry Building Society reports interest to HMRC, so your tax code is usually adjusted automatically.